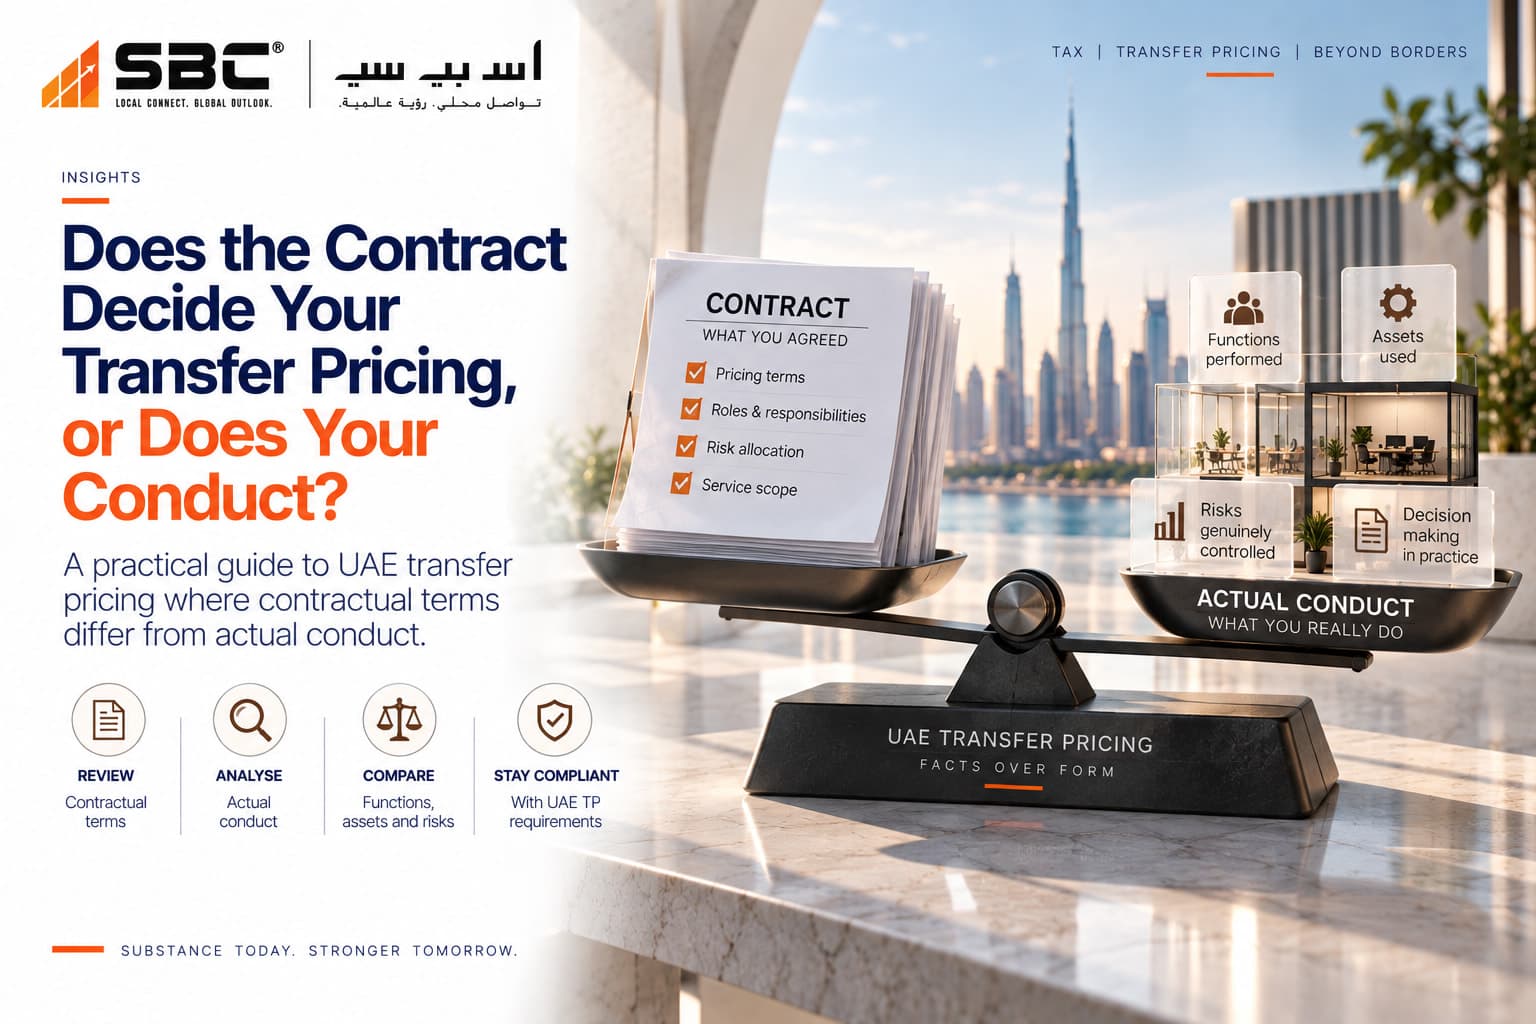
A signed intercompany agreement is the starting point of a UAE transfer pricing analysis, not the end of it. Where related parties actually operate differently from what the paperwork says, the Federal Tax Authority tests the arm's length outcome against the functions performed, assets used and risks genuinely controlled in practice.
Key official references include UAE Corporate Tax Law: Article 34 on the Arm's Length Principle, the UAE Federal Tax Authority Transfer Pricing Guide and the FTA Advance Pricing Agreements Guide. Related questions sit in intercompany agreements, functional analysis and from policy to invoice.
Many UAE groups hold intercompany agreements that were drafted years ago for commercial, banking or corporate governance reasons, long before Corporate Tax existed. Roles have since evolved, teams have grown or shrunk, and pricing decisions are frequently made informally between finance managers rather than through a documented policy. Corporate Tax exposes this gap. Under the arm's length principle, a related party transaction is priced according to what happened economically, and a contract that no longer reflects that reality can leave a business defending a position the facts do not support. See also FTA guidance on Related Parties and Article 35.
Why isn't a signed agreement enough for UAE transfer pricing purposes?
Because a contract records what the parties intended to agree, not necessarily what they actually did. The FTA Transfer Pricing Guide adopts a substance-over-form approach: the economic conduct of the parties, evidenced through the functions performed, assets employed, risks assumed, economic circumstances and business strategies, carries more weight than the written label attached to a transaction. Article 34 of the UAE Corporate Tax Law requires the arm's length result to be tested against an accurately delineated transaction, and delineation is a factual exercise, not a contractual one. This mirrors the approach set out in the OECD Transfer Pricing Guidelines following the BEPS Actions 8-10 revisions to Chapter I.
What does accurately delineating a controlled transaction actually involve?
It means reconstructing the transaction from the facts before pricing it. The starting point is still the written terms, since they generally reflect what independent parties would also record. From there, the analysis tests whether the conduct of the parties is consistent with those terms, or whether it diverges in a way that changes the economic substance of the arrangement. Where a divergence exists, the actual conduct governs the pricing analysis.
How does risk allocation work when the contract and the conduct disagree?
Risk allocation follows control, not merely contractual assumption. Under the framework applied in the FTA Guide and consistent with OECD Chapter I, an economically significant risk is first identified, the party contractually assuming it is noted, and the analysis then tests which party actually exercises control over that risk (through decision-making capability and the capacity to respond to risk outcomes) and which party has the financial capacity to bear it. If the party named in the contract neither controls the risk nor has the financial capacity to absorb its consequences, the risk is treated, for pricing purposes, as belonging to the party that does.
Can the FTA depart from the legal form of a transaction altogether?
There is an important distinction between re-characterising the pricing of a transaction and disregarding the transaction entirely. Adjusting the return earned by a party because its actual functions, assets and risks differ from the contract is a routine, and comparatively common, outcome of an accurate delineation exercise. Non-recognition of the arrangement as a whole is a narrower and more exceptional step, generally reserved, under OECD guidance, for arrangements that lack the commercial rationality that independent parties would exhibit. This is an area where the specific facts, and the quality of contemporaneous evidence, matter considerably, and the position should not be assumed one way or the other without a documented analysis.
The FTA's wider corporate tax guidance can be reviewed through FTA Corporate Tax Guides and References.
A practical illustration
A UAE entity is described in its distribution agreement as a limited risk distributor, remunerated on a fixed operating margin. In practice, the entity negotiates purchase prices with regional suppliers without reference to the principal, carries inventory for an average of ninety days, and has absorbed bad-debt write-offs in two of the last three years without any corresponding adjustment from the principal. The functional reality points toward a more entrepreneurial risk profile than the contract describes. Left unaddressed, this gap is exactly the kind of inconsistency a transfer pricing review, whether internal or by the FTA, is designed to identify, and it can support a higher expected return than the fixed margin the agreement specifies.
What should the file show when there is a gap between the agreement and actual practice?
-
The current intercompany agreement, together with any prior versions and amendment history.
-
Evidence of decision-making, such as approval emails, board minutes or pricing committee records, showing who actually exercises control over key functions.
-
Organisational charts and job descriptions reflecting current, not historical, roles.
-
Records showing which entity has borne cost overruns, inventory write-downs, bad debts or warranty claims.
-
A short reconciliation memo explaining any divergence between contract and conduct and the pricing conclusion adopted as a result.
-
Where the agreement has been updated to reflect current practice, a record of when and why that update was made.
See FTA guidance on Transfer Pricing Documentation and Local File and, where thresholds apply, what a UAE Local File should contain.
Key takeaways
-
A written agreement is evidence of intended terms; it is not, by itself, proof of the arm's length outcome.
-
Accurate delineation under Article 34 tests the transaction against actual functions, assets, risks, economic circumstances and business strategies.
-
Risk sits with the party that controls it and can financially bear it, regardless of which party the contract names.
-
Disregarding a transaction entirely is an exceptional outcome; adjusting its pricing to match conduct is far more common.
Who should reconcile the legal agreements with actual practice?
Tax, legal and finance, working together, on a periodic basis rather than only when a dispute arises. Legal understands what the agreement says, finance understands where the money and risk actually sit, and tax understands what Article 34 requires the two to demonstrate together. A short annual review, timed to coincide with the Local File update where one is required, is generally a more efficient way to close this gap than reconstructing the analysis retrospectively during an FTA enquiry.
For the overall UAE corporate tax context, see the FTA Corporate Tax portal. Cross-check the same facts against policy versus documentation and how to identify related parties.
How should a UAE finance team start with the facts rather than the tax result?
A strong transfer pricing position starts with the transaction itself. A finance team should first identify what was actually supplied, who performed the work, where the people and assets were located, which entity carried the commercial risk, and what the accounting records show. The tax result should come after that fact pattern is clear. This is especially important in the UAE because the arm's length analysis is not limited to the wording of an invoice. The commercial substance of the arrangement determines which comparability questions need to be answered.
For a UAE group, the practical exercise is usually to build a transaction inventory. List each related party and connected person, describe the transaction, identify the contractual terms, record the annual value, and note the pricing method currently used. Then compare that list with the general ledger, intercompany confirmations, contracts, and tax return disclosures. Differences between those records are often more important than a small difference in the final margin. They can show that the group has not consistently applied its own policy. FTA guidance on Connected Persons and Article 36
The FTA also explains the arm's length principle in its FTA Transfer Pricing FAQ.
The FTA's Transfer Pricing Guide is useful as the starting reference because it explains the UAE framework, related party concepts, arm's length analysis and documentation expectations. A finance team should read the guide together with the Corporate Tax Law and the relevant implementing decisions rather than treating a summary article as the legal source.
Why does the functional analysis matter more than the label used in the agreement?
The label of a UAE entity does not determine its transfer pricing outcome. A company described as a distributor may in practice perform substantial marketing, inventory management, credit control and market development functions. Similarly, an entity called a service company may employ senior decision makers, own important assets or assume significant commercial risk. The functional analysis tests what the business actually does.
A useful functional analysis records functions, assets and risks separately. Functions include procurement, sales, manufacturing, logistics, marketing, treasury, management and technology support. Assets include tangible operating assets, working capital and relevant intangible assets. Risks include inventory, foreign exchange, credit, market, product and capacity risk. The analysis should identify who controls each economically significant risk and who has the financial capacity to bear it.
This approach also makes the benchmarking exercise more defensible. If the tested party is selected because it performs routine distribution functions, the comparable set should reflect businesses with similar functions and risk. If the facts show a more complex business, a routine TNMM analysis may need to be reconsidered. The OECD framework and the FTA guide both emphasise comparability and accurate delineation rather than relying on a label alone. FTA Transfer Pricing Methodologies FAQ
How can a UAE group make its transfer pricing evidence consistent with its accounting records?
A defensible file should tell the same story as the books. The intercompany agreement should describe the transaction in a way that is consistent with invoices, ledger accounts, payment flows and the actual conduct of the parties. If the agreement says that a UAE company provides management support but the ledger shows substantial royalty payments, the file should explain the distinction. If a policy says a distributor earns a routine margin but the accounts contain large year-end service charges, the reason should be documented.
The documentation framework is set out by the Ministry of Finance in its Ministry of Finance transfer pricing documentation decision. Ministerial Decision No. 97 of 2023 on Transfer Pricing Documentation
The practical control is a transaction reconciliation. Start with the related party ledger and map each material account to the relevant agreement and transfer pricing policy. Reconcile the annual value to the disclosure position. Then check whether the pricing method and tested party in the study correspond to the transaction that was actually booked. This is a simple exercise, but it can identify problems before an FTA request.
The FTA documentation guidance is particularly useful here because documentation is not only a narrative exercise. The purpose is to enable the taxpayer to demonstrate how the arm's length outcome was reached. Good documentation therefore connects the facts, method, comparables, calculations and financial data.
What should management review before signing off the UAE transfer pricing position?
Management should be able to answer five practical questions. What related party transactions occurred? Why did the group choose the pricing method? What evidence supports the price or margin? Does the actual year-end result remain within the intended policy? And can the business reproduce the analysis if the FTA asks for it?
A senior review should also consider changes during the year. A new shareholder, new financing arrangement, new distribution model, major acquisition, new intellectual property arrangement or change in business strategy can affect the comparability analysis. A study prepared at the beginning of the year does not automatically remain appropriate when the operating model changes.
The detailed statutory requirements should be read with Ministerial Decision No. 97 of 2023.
For UAE groups with operations across several jurisdictions, management should also consider consistency between countries. The same transaction may be reviewed by two tax authorities. A position that is accepted in one country may create an adjustment elsewhere if the functional story is inconsistent. That is why the UAE file should be prepared as part of the group's wider transfer pricing governance rather than as a document created only for the UAE tax return.
How should a business prepare for an FTA transfer pricing review?
Preparation should focus on speed, consistency and evidence. The business should know where the current agreements, benchmarking study, transaction schedule, calculations and supporting invoices are stored. The people responsible for tax, finance and the relevant business function should also understand the commercial background well enough to explain the transaction without relying entirely on the adviser who prepared the report.
An audit-ready file normally includes the legal basis, organisational structure, transaction descriptions, functional analysis, selected method, comparability analysis, financial calculations and supporting documents. It should also contain a clear bridge from the tested party's statutory accounts to the financial information used in the benchmarking analysis. Where adjustments have been made, the file should explain why.
The FTA's published materials should be treated as the primary reference point. Where an issue is not answered clearly in a guide, the business should avoid creating a technical conclusion simply because a secondary source says it is common practice. The better approach is to identify the uncertainty, review the legislation and official guidance, and document the judgement applied.
How should a UAE benchmarking study explain the selection of comparables?
A good benchmarking study does not begin with a database screen and end with a percentile range. It explains why the selected companies are economically comparable to the tested party. The search strategy should be understandable to a reader who was not involved in preparing the study.
Where the legal basis needs to be checked, refer to the UAE Corporate Tax Law.
The analysis should explain the tested party, geographic market, industry, functions, assets and risks. It should state the financial period used, screening criteria, reasons for rejecting material candidates and any adjustments made. If the final set is small, the report should explain why. If the set is broad, it should explain why the differences do not undermine reliability.
This is particularly important when an FTA reviewer challenges a comparable. The strongest response is not that the company appeared in a commercial database. It is that the company satisfies the relevant comparability factors and that the differences have been assessed. The OECD Transfer Pricing Guidelines provide the wider international framework for this comparability analysis.
What should a UAE company do when its actual margin is outside the benchmark range?
An outside-range result should trigger an investigation, not an automatic accounting entry. Management should first establish whether the actual result reflects genuine commercial conditions. A distributor may have earned a lower margin because freight costs increased, a new market was entered, inventory became obsolete or the company incurred one-off launch expenses. Those facts may explain the outcome, but they do not automatically prove that the transfer price was arm's length.
The next step is to compare the actual functions and risks with the tested party profile in the benchmarking study. If the business has changed, the study may no longer be reliable. If the business has not changed, management should analyse whether the deviation is temporary or structural. The conclusion should then be documented before any year-end true-up is considered.
A year-end adjustment should be supported by the transfer pricing policy, contractual framework, accounting treatment and tax consequences. It should not be used merely to force the accounts into the middle of a statistical range.
For advance pricing agreement considerations, the FTA provides its FTA Advance Pricing Agreement Guide.
What should be checked at year end before the UAE transfer pricing file is closed?
Year end is where the policy meets the actual numbers. The finance team should compare the agreed pricing mechanism with the recorded transactions and calculate the resulting margin or price. If the result differs materially from the policy expectation, the difference should be investigated before a true-up is booked.
The review should also consider whether the underlying business changed during the year. A new customer segment, supply chain change, new financing, acquisition or restructuring can affect comparability. A transfer pricing file that accurately described the business in January may not fully describe it in December.
The final review should be documented with a short management conclusion. That conclusion should explain whether the policy was applied, whether any adjustment was required and what evidence supports the decision.
How can the technical conclusion be kept practical for UAE management teams?
Transfer pricing is ultimately a business process. The tax department may own the technical analysis, but finance owns the numbers, legal owns many agreements, treasury owns financing, HR owns employee arrangements and business teams understand the commercial reality. A useful UAE policy connects those functions instead of leaving transfer pricing as an isolated annual report.
The FTA's general corporate tax guidance is available in the FTA Corporate Tax General Guide.
For management, the most useful output is a short dashboard showing related party transactions, material movements, current benchmark status, disclosure position, documentation readiness and open technical questions. The detailed report remains important, but the dashboard helps management act before a compliance deadline.
This practical approach also improves the quality of future benchmarking. Each year the group already has a reliable transaction inventory and evidence trail, so the adviser spends more time on technical analysis and less time reconstructing the facts.
What questions is a UAE tax reviewer likely to ask first?
The first questions are usually factual. What is the transaction? Who are the parties? What does each party actually do? Why was the price set this way? What evidence supports the price? How was the tested party selected? Which comparables were considered? How does the result reconcile to the accounts?
A taxpayer should be able to answer these questions consistently across its agreement, TP report, tax return and financial statements. If different documents tell different stories, the reviewer may spend more time testing the transaction.
Preparing these answers in advance is one of the simplest ways to improve the quality of a transfer pricing position. It also forces the business to identify gaps while there is still time to fix them.
For current implementing legislation and FTA decisions, consult the FTA Corporate Tax legislation page.
Official government and international references
For the domestic legal framework, refer to UAE Corporate Tax, Ministry of Finance. FTA FAQ on Domestic and Cross-Border Transfer Pricing
The main FTA guidance is available in FTA Transfer Pricing Guide.
The FTA also maintains current references in FTA Corporate Tax Guides and Public Clarifications.
The FTA explains the core concept in its FTA Transfer Pricing FAQ.
For documentation questions, see FTA Transfer Pricing Documentation FAQ.
The Ministry of Finance explains the documentation framework in Ministry of Finance Transfer Pricing Documentation Decision.
For the international arm's length framework, see OECD Transfer Pricing topic.
For the detailed OECD methodology, see OECD Transfer Pricing Guidelines 2022.
A practical action plan for UAE groups
-
Map all related parties, connected persons and transaction categories against the legal entity structure and general ledger.
-
Document the commercial facts, including functions, assets, risks, contractual terms and actual conduct.
-
Select and document the most appropriate transfer pricing method and explain why the method fits the transaction.
-
Test the pricing or margin against reliable comparable evidence and record the reasons for accepting or rejecting material comparables. OECD Transfer Pricing Guidelines
-
Reconcile the final transfer pricing result to the statutory accounts, intercompany invoices and Corporate Tax return data.
-
Complete the relevant disclosure and documentation checks before the filing process is closed, and retain supporting evidence in an accessible audit file.
Frequently asked questions
Does a signed intercompany agreement decide the UAE transfer pricing outcome?
No. The agreement is evidence of intended terms. Article 34 tests the arm's length result against the accurately delineated transaction, which follows actual functions, assets, risks, economic circumstances and business strategies where those facts diverge from the paperwork.
What happens when the contract and actual conduct disagree?
The actual conduct governs the pricing analysis. Risk sits with the party that controls it and has the financial capacity to bear it, even if another party is named in the contract.
Can the FTA disregard a related party transaction entirely?
In principle yes, but this is treated as an exceptional outcome under the framework the UAE has adopted, generally reserved for arrangements lacking commercial rationality. Most divergences between contract and conduct are addressed through re-pricing rather than non-recognition.
Does actual conduct override the contract for legal or accounting purposes too?
No. The analysis is specific to how a transaction is characterised and priced for transfer pricing purposes. It does not itself change the legal validity or accounting treatment of the underlying agreement.
How often should intercompany agreements be reviewed?
At least annually as part of the transfer pricing documentation cycle, and additionally whenever a restructuring, new product line, system migration or personnel change materially affects who performs the relevant functions. A material shift in functions, assets or risk-bearing should be reflected in the agreement and in the pricing policy within a reasonable time.
Does the UAE arm's length principle apply to domestic related party transactions?
Yes. The UAE framework applies to relevant related party and connected person transactions regardless of whether the counterparty is in the UAE or outside the UAE, subject to the applicable rules and definitions. See do domestic related party transactions need transfer pricing in the UAE.
When should a UAE business refresh its transfer pricing analysis?
The analysis should be reviewed when the business, transaction, functions, assets or risks change materially. Comparable financial data should also be kept current in line with the taxpayer's benchmarking approach.
What evidence should be retained for an FTA review?
Retain agreements, invoices, transaction schedules, functional analysis, benchmarking support, calculations, allocation keys, approvals and the evidence used to reconcile the TP result to the accounts.
Is a benchmarking report enough to support an arm's length position?
Not by itself. The report should explain the transaction, functional profile, method selection, comparable selection, financial calculations and the link between the tested result and the accounting records.
Can the actual year end result differ from the transfer pricing policy?
Yes, but the difference should be investigated and documented. A year end true up should be supported by the commercial facts, policy, contractual framework and applicable tax and accounting treatment.
How should management respond when the transaction facts change during the year?
The change should be documented promptly. A new financing arrangement, acquisition, restructuring, new service, change in functions or major market change can affect the existing analysis and should trigger a review.
Which official sources should a UAE taxpayer check before relying on transfer pricing guidance?
Start with the official Ministry of Finance and Federal Tax Authority materials in the UAE. For international methodology, the OECD Transfer Pricing Guidelines are the main reference. For Saudi matters, use ZATCA's published regulations and guidance.
Primary sources and further reading
-
UAE Corporate Tax Law: Article 34 on the Arm's Length Principle
-
Ministerial Decision No. 97 of 2023 on Transfer Pricing Documentation
How SBC Tax Consulting can help
SBC's transfer pricing team reconciles intercompany agreements with actual functions, assets and risks, then builds the Local File evidence trail. Contact SBC before the next FTA request, year-end true-up or agreement refresh.
This publication is for general information only and does not constitute professional advice. Please consult your SBC advisor before acting on any matter covered here.