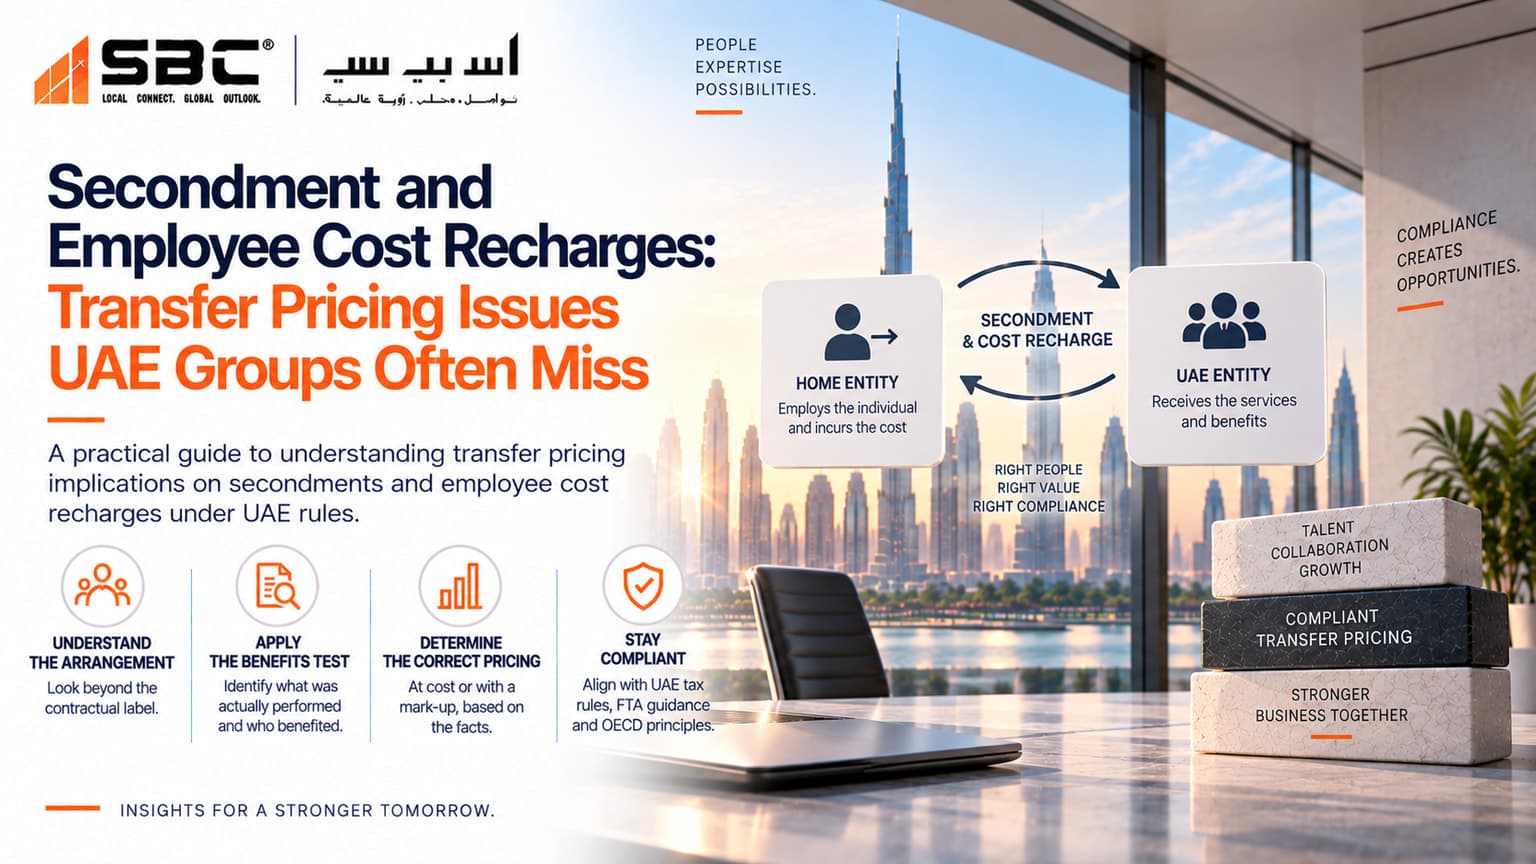
Employee cost recharges look like a payroll allocation. Under Article 34 of Federal Decree-Law No. 47 of 2022 they are intra-group services. A group company that employs people centrally and recharges a UAE entity — or seconds staff into the UAE — still has to show what activity was performed, who benefited, and what an independent party would have paid. Identifying the salary and adding a mark-up is not the analysis.
The FTA Transfer Pricing Guide (CTGTP1) applies the same benefit test used for other intra-group services. The contractual label — secondment, recharge, management support, "at cost" — does not determine the transfer pricing treatment. Related questions sit in management fees and the benefit test and intragroup services.
What is the difference between a secondment and an employee cost recharge?
A secondment typically places an employee under the day-to-day direction of the host entity for a defined period. The host often looks, commercially, like the employer of the person's time: it controls the work, receives the output, and would otherwise have hired locally.
An employee cost recharge is usually a service. The employing entity keeps control of the people, performs activities for one or more recipients, and invoices a share of cost — with or without a mark-up.
Those two fact patterns are not interchangeable. If the "secondee" remains managed by the parent, reports into a regional function and only sits in the UAE office, the arrangement may be a service even if the paperwork says secondment. If the UAE entity directs the person, sets objectives and bears the output risk, a pure cost recharge with a service mark-up may overstate what the provider actually did. The functional analysis has to follow who controls the work.
How does the benefit test apply to people costs?
The starting point is whether the recipient received an identifiable economic or commercial benefit. An activity is generally chargeable where an independent enterprise in comparable circumstances would have paid another party to perform it, or would have performed it internally.
For employee-related arrangements that means identifying the actual activities, not treating the entire payroll line as a chargeable service. Useful questions:
-
What did the employee actually do?
-
Which entity benefited from the activity?
-
Was the activity required for the recipient's business?
-
Would the recipient have incurred a similar cost independently?
-
Did the provider perform a service, or merely incur a cost on behalf of the recipient?
Which people costs should not be recharged at all?
Not every activity a parent undertakes in relation to a subsidiary is a chargeable intra-group service. Where the work exists solely because of the group's ownership interest — stewardship — the cost generally should not be charged to the UAE entity.
Typical exclusions include shareholder meetings, parent-level governance, preparation of consolidated financial statements for the parent's own reporting, investor relations, and activities undertaken solely to meet the parent's regulatory requirements. The facts still have to be tested in each case: a regional HR business partner who also sits on the parent's remuneration committee may be doing both chargeable and non-chargeable work in the same week.
At cost, or with a mark-up?
There is no blanket rule that every employee cost recharge should be at cost. The appropriate treatment follows the nature of the arrangement.
Where the host is in substance the employer for the period — it directs the secondee, the provider is only a payroll conduit, and no additional service is being supplied — a recharge of the relevant employment cost with no mark-up can be the arm's length result, provided the cost base is clean.
Where the provider is delivering a service through its people, a mark-up is usually expected. The UAE framework, consistent with OECD Chapter VII, provides a simplified 5% cost mark-up for qualifying low value-adding intra-group services. That shortcut does not attach to every people recharge. The service should be supportive, not part of the group's core business, not reliant on unique intangibles, and not associated with significant risk. Core operational, sales, technical and decision-making roles sit outside the simplified approach and need their own method and comparables.
Pass-through items — visa fees paid as agent, or a third-party recruiter invoice incurred solely for the host — should not automatically pick up the same mark-up as the provider's own service.
How should an allocation key be chosen?
Where a centralised employee-related service benefits several entities, the allocation key should reflect how the benefit is received. Revenue is not automatically the right driver for every people cost.
Headcount is often a better fit for HR administration; active user counts for IT support; project hours for a seconded specialist. A regional company that incurs AED 600,000 of HR-related cost, of which AED 120,000 is stewardship, should exclude the stewardship slice first, identify which entities actually received the remaining service, allocate on a benefit-based key, then decide whether the 5% simplified approach applies or a separate mark-up study is required.
Duplication matters as well. If the UAE subsidiary already has its own HR team, a parent recharge for substantially the same work needs a documented commercial reason — a transition, a specialised overlay — or it will fail the benefit test.
What should the documentation cover?
-
A written secondment or services agreement stating who employs the person, who directs the work, the term, the cost base and any mark-up.
-
Roles, reporting lines and a description of activities actually performed.
-
Identification of beneficiaries and the benefit each received.
-
The cost base, excluded stewardship and pass-through items, and the allocation key.
-
Timesheets, payroll records, invoices, organisational charts and, where relevant, evidence that the host would otherwise have hired locally.
-
Confirmation of whether the arrangement is a service, a secondment, or a mix.
For Taxable Persons that meet the thresholds under Ministerial Decision No. 97 of 2023, this material belongs in the Local File.
If the individual is an owner, director or officer of the UAE entity, Connected Persons rules under Article 36 can apply to the same amounts on top of Article 34.
What mistakes do UAE groups commonly make?
-
Treating every payroll recharge as automatically "at cost" without testing who controls the work.
-
Applying a 5% mark-up to secondments, core technical roles or shareholder activities because the simplified approach is easy.
-
Charging the UAE entity for work it already performs locally, with no explanation of the extra benefit.
-
Marking up visa, recruitment or other third-party disbursements as if they were the provider's own service.
-
Having no secondment agreement, or an agreement that says the host directs the employee while emails and appraisals show the parent still does.
-
Ignoring that a long-term "secondment" of a decision-maker can look like a permanent establishment or a change in the UAE entity's functional profile, not merely a people cost.
Frequently asked questions
Can employee costs simply be recharged at cost with no mark-up?
Sometimes, where the host is in substance the employer for the period and the provider is only a payroll conduit. If the provider is delivering a service through its people, a mark-up is usually expected.
Does the 5% simplified approach apply to every secondment?
No. The simplified 5% cost mark-up is limited to qualifying low value-adding intra-group services. Seconded operational, sales, technical or decision-making roles generally sit outside that shortcut.
Should shareholder and stewardship time be included in the recharge?
No. Activities performed solely because of the parent's ownership interest should be excluded from the chargeable cost base.
What if the UAE entity already employs people to do the same work?
Duplication has to be examined. It can be justified during a transition or where the recharge is for specialised overlay work, but the extra benefit needs to be documented.
Can a seconded director or officer also be a Connected Person issue?
Yes. If the individual is a director, officer or owner of the UAE entity, Article 36 Market Value testing can apply to the same payments in addition to the Article 34 analysis.
Primary sources and further reading
-
Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses — Articles 34 and 36
-
OECD Transfer Pricing Guidelines — Chapter VII, intra-group services
How SBC Tax Consulting can help
SBC's transfer pricing team separates secondments from intra-group services, excludes stewardship from the cost base, and documents whether a nil mark-up or a benchmarked return is the arm's length result. Corporate tax specialists then keep Connected Persons, Permanent Establishment and Local File positions on the same facts. Contact SBC before the next regional secondment or year-end recharge.
This publication is for general information only and does not constitute professional advice. Please consult your SBC advisor before acting on any matter covered here.