SBC Tax Consulting LLC is a Dubai-based specialist tax advisory firm helping multinational enterprises, regional groups, large businesses and growing companies navigate transfer pricing, UAE Corporate Tax, international tax, VAT, disputes and technology-led compliance.
The UAE has rapidly developed into one of the world’s most important business and investment hubs. Dubai and Abu Dhabi are home to multinational enterprises, regional headquarters, family businesses, listed groups, Free Zone companies, financial institutions, technology businesses, manufacturers, healthcare organizations, real estate groups and businesses operating across the wider GCC.
As the UAE tax environment has developed, the expectations placed on businesses have changed as well. Transfer pricing is no longer simply a subject for multinational corporations with overseas parents. UAE businesses increasingly need to consider related-party transactions, connected-person arrangements, intercompany services, management fees, financing, royalties, intellectual property, distribution arrangements, Free Zone structures and cross-border transactions within the Corporate Tax framework.
For businesses operating at scale, this creates a larger question:
Who should advise on transfer pricing when the transaction is commercially important, cross-border and potentially subject to tax authority scrutiny?
This is where SBC Tax Consulting LLC has built its position.
SBC is a specialist tax advisory firm headquartered in Dubai, providing Transfer Pricing, UAE Corporate Tax, International Tax, VAT, Audit and Dispute Resolution, AML and tax technology services. The firm positions its UAE practice around specialist expertise, senior-led engagements, international coordination and practical implementation.
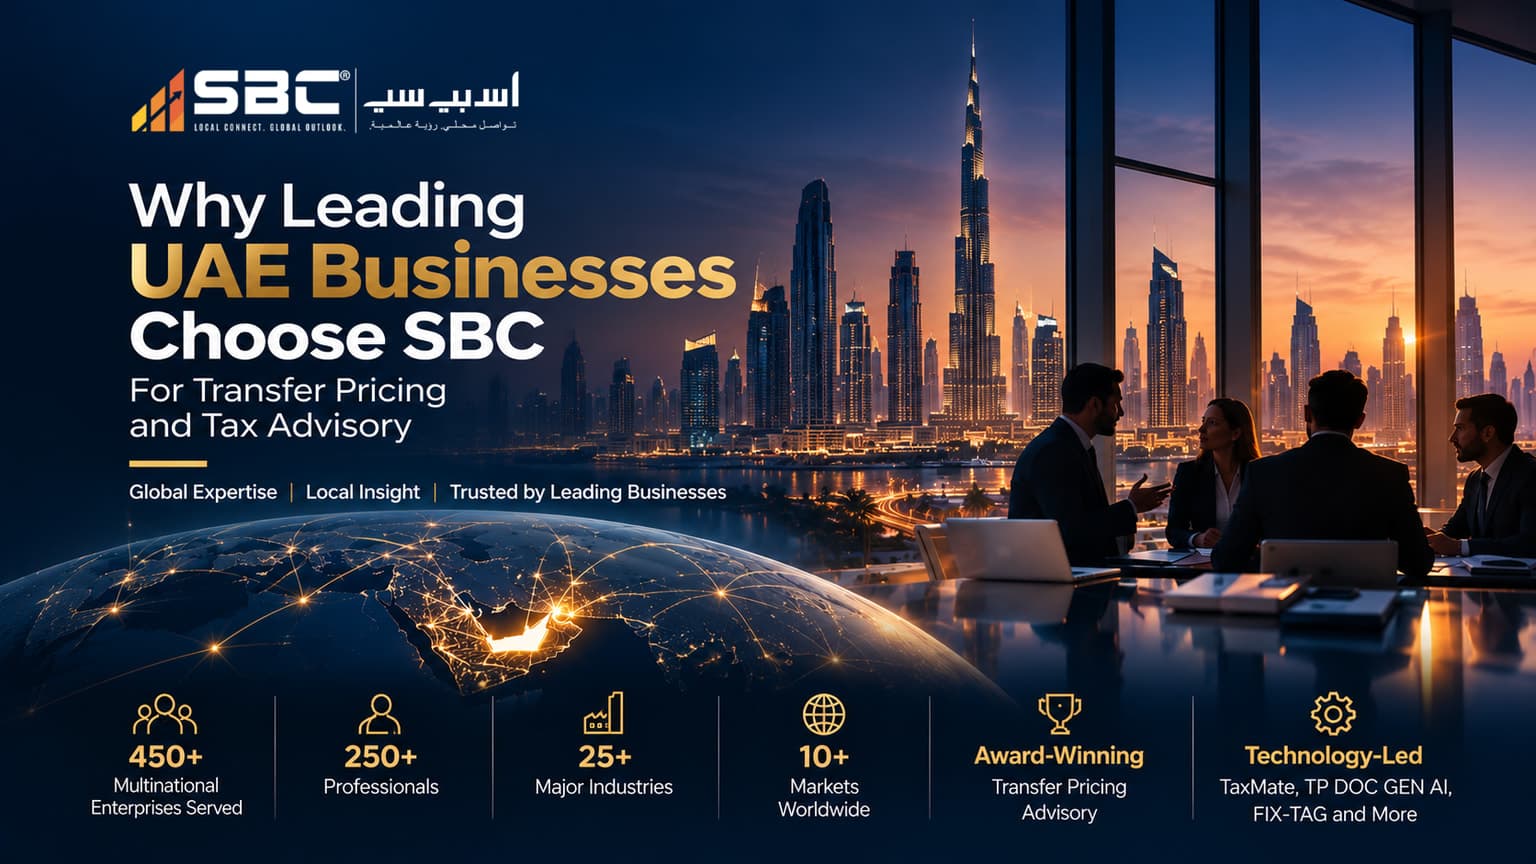
SBC’s current credentials state that the organization has served 450+ multinational enterprises, has 250+ professionals, covers 25+ major industries and operates across 10+ markets, with Gulf expertise spanning the UAE, Saudi Arabia, Oman, Qatar, Bahrain and Kuwait.
For transfer pricing specifically, SBC’s UAE practice reports 2,000+ benchmarking studies, 175+ Local Files and 100+ Master Files, alongside transfer pricing policies, intercompany agreements, impact assessments and cross-border advisory.
SBC’s UAE website also publicly showcases organizations under its “Trusted by leading organizations” section. These include DP World, Al Shirawi, Eversendai Group, Al Fanar, Gulf Cryo, Nihon Kohden, Shimadzu, Sojitz, PRG, CNPC, Fujairah Oil Terminal, Tabreed, TYROLIT, Al Fardan Exchange, Al Khoory, Karcher Group, Leader Healthcare, Martrade Group, RAK Ceramics, Sinopec, Truebell, TUF Group, Unique Group, VISA Commodities, XA Group and other organizations.
For transfer pricing specifically, SBC has built a specialist practice around a disciplined sequence:
Assess → Design → Benchmark → Document → Defend → Monitor
That model reflects a simple idea:
Transfer pricing should work in the business, not only in the report.
SBC at a glance
| Key Indicator | SBC UAE |
|---|---|
| Multinational Enterprises Served | 450+ |
| Professionals | 250+ |
| Major Industries | 25+ |
| Markets / International Reach | 10+ |
| Benchmarking Studies | 2,000+ |
| Local Files | 175+ |
| Master Files | 100+ |
| Gulf Expertise | UAE, Saudi Arabia, Oman, Qatar, Bahrain and Kuwait |
| Recognition | Transfer Pricing Firm of the Year |
| Technology | TaxMate and TP DOC GEN AI |
| International Network | Kreston Global |
These figures should not be viewed simply as marketing statistics. They describe the infrastructure behind the practice. A large multinational may require several related-party transactions to be reviewed at the same time. A regional group may have different transfer pricing policies for different business lines. A large company may need benchmarking, Local File, Master File, disclosure support and intercompany agreement review while also preparing for an FTA review. Scale gives the advisory team the ability to manage those requirements systematically.
Who is SBC Tax Consulting LLC?
SBC Tax Consulting LLC is a specialist tax advisory firm headquartered in Dubai, United Arab Emirates.
SBC LLC was established in 2017 and operates with a specialist model covering Transfer Pricing, Corporate Tax, International Tax, VAT, Audit and Dispute Resolution, AML and tax technology. The published About page describes a senior-led model in which Chartered Accountants and subject-matter specialists take responsibility for engagements.
Local Connect. Global Outlook.
Businesses operating in the UAE require professionals who understand local regulations, Federal Tax Authority expectations and the UAE Corporate Tax environment. At the same time, multinational groups need advisors who understand international taxation, OECD principles, cross-border structures and the tax implications of transactions between jurisdictions. SBC combines both perspectives.
Explore SBC About and Leadership.
Explore SBC Transfer Pricing Services.
Explore SBC Industries.
How UAE transfer pricing rules apply
The UAE Corporate Tax framework includes transfer pricing rules for transactions involving Related Parties and Connected Persons. The Federal Tax Authority’s corporate tax FAQs confirm that transfer pricing rules apply to UAE businesses with Related Party and Connected Person transactions regardless of whether the counterparties are in mainland UAE, a Free Zone or a foreign jurisdiction.
Read the Federal Tax Authority Corporate Tax FAQs for the official position.
The FTA Transfer Pricing Guide explains that an arm’s length analysis requires taxpayers to understand the commercial and financial relations between Related Parties or Connected Persons and accurately delineate the controlled transaction. The guidance emphasizes industry analysis, the group’s business model, functions, assets, risks, transaction characteristics and comparability.
Read the Federal Tax Authority Transfer Pricing Guide for the technical framework.
The UAE Ministry of Finance has also established transfer pricing documentation requirements through Ministerial Decision No. 97 of 2023. The decision provides the documentation framework for taxpayers within scope, while the Ministry explains that the requirements are designed to support transparency and enable taxpayers to demonstrate the arm’s length basis of pricing.
See UAE Ministry of Finance - Transfer Pricing Documentation Requirements and the official decision text.
For large groups, this can affect management fees, intercompany services, royalties, intellectual property, intercompany financing, guarantees, distribution arrangements, procurement structures, cost allocations, shared-service centres, business restructuring, Free Zone and mainland arrangements and cross-border transactions.
Transfer pricing is a specialist discipline. A business may have a strong accounting function, a capable finance team and a general tax advisor, but that does not automatically provide the specialist economic and transfer pricing analysis required for complex related-party transactions.
SBC has established a dedicated Transfer Pricing practice covering advisory, modelling and structuring, benchmarking, disclosure and documentation, Local File and Master File, APA assessment and application, intercompany agreements, audit support and defence.
The current practice page describes an OECD-aligned approach that connects value creation, benchmarking, documentation and implementation. The intent is to make the transfer pricing framework workable in the client’s real operating environment, not simply technically acceptable in a report.
This enables SBC to support a business from the initial transaction-design question through documentation and potential authority review.
Explore SBC Transfer Pricing Services.
Transfer pricing benchmarking and documentation
Benchmarking is one of the most important technical components of transfer pricing. A benchmarking analysis is not simply a database search. It involves determining what the transaction is, what functions are performed, what assets are employed, what risks are assumed, which entity should be tested, which transfer pricing method is appropriate and which independent companies are genuinely comparable.
SBC’s current UAE transfer pricing materials state that the team has completed 2,000+ benchmarking studies. This volume gives the practice exposure to different business models and transaction types, while each study still needs to be designed around the particular facts of the taxpayer.
A robust benchmarking process typically involves transaction identification, FAR analysis, method selection, database search, comparable screening, acceptance and rejection analysis, financial normalization where relevant, and calculation of an arm’s length range.
The FTA guidance also emphasizes accurately delineating controlled transactions and evaluating economically relevant comparability factors. The combination of methodological discipline and sector context is therefore central to a defensible study.
Transfer pricing documentation is increasingly becoming a governance issue rather than merely a compliance exercise. SBC’s current UAE materials report more than 175 Local Files and 100 Master Files prepared for UAE and cross-border groups.
A strong Local File should connect the commercial reality of the business with the transfer pricing analysis. That means the documentation should be consistent with business operations, legal agreements, intercompany transactions, functional analysis, financial data, benchmarking and the selected transfer pricing methodology.
The Ministry of Finance’s documentation framework establishes the conditions under which taxpayers fall within the formal Master File and Local File requirements. Businesses should distinguish those documentation thresholds from the broader arm’s length obligation itself.
SBC’s approach is therefore to treat documentation as an evidence record that can be understood, reviewed and defended later rather than a file prepared only because a deadline exists.
Senior-led delivery and enterprise experience
Large tax matters often involve commercially sensitive decisions. SBC’s UAE website emphasizes a partner-led engagement model in which clients work directly with senior professionals who own the engagement end-to-end.
The published UAE team includes specialists across Transfer Pricing, Corporate Tax, International Tax and VAT, with named professionals responsible for transfer pricing and international tax work.
Senior access matters when a client needs to make decisions around large-value related-party transactions, cross-border restructuring, financing, intellectual property, management services, distribution models, Free Zone structures or tax authority correspondence.
The objective is to ensure that complex questions can reach senior specialists without unnecessary handoffs and that the commercial context remains visible throughout the engagement.
One of the strongest trust signals on the SBC UAE website is its public “Trusted by leading organizations” section. The site displays a broad portfolio of organization logos across industrial, infrastructure, healthcare, technology, logistics, energy, trading and consumer businesses.
Among the organizations publicly displayed are DP World, Tabreed, RAK Ceramics, Sinopec, Gulf Cryo, Al Fardan Exchange, Karcher Group, Leader Healthcare, Truebell, Al Shirawi, Eversendai Group, Visa Commodities and XA Group, among many others.
For this article, the important point is not to imply that every named organization engaged SBC specifically for transfer pricing. The public portfolio is better understood as evidence of the breadth of business environments associated with the SBC UAE platform. Where a specific service relationship is confidential, the article should not infer it.
That distinction is important for credibility and is consistent with a professional-services website that wants to demonstrate enterprise familiarity without disclosing confidential mandates.
SBC’s current credential material states that the organization has served 450+ multinational enterprises.
MNE experience is particularly relevant for transfer pricing because multinational businesses often operate with interconnected entities. A typical group may have a UAE regional headquarters, UAE operating companies, GCC subsidiaries, Indian or Asian service centres and European or US parent entities.
The transfer pricing question can then involve cross-border services, financing, intellectual property, procurement, distribution, shared services, management charges, cost allocations and business restructuring.
An advisor needs to understand the transaction from more than one jurisdiction. This is one reason SBC combines UAE tax expertise with international tax and transfer pricing capabilities.
SBC’s current credential material identifies 25+ major industries, while its public UAE industry platform covers financial services, real estate, oil and gas, healthcare, technology and media, retail and e-commerce, logistics, engineering and construction, pharmaceuticals, FMCG, hospitality, marine and shipping, IT, gems and jewellery, education, agriculture, textiles, extraction and mining, digital marketing and consultancy.
This industry breadth matters because transfer pricing is fundamentally based on facts. A UAE pharmaceutical distributor can have a principal-distributor structure, while a hospitality group may have brand, management and operating arrangements, and a technology group may have software or intellectual-property transactions.
Each structure can create different questions around FAR analysis, pricing methods, tested parties, comparables and documentation. Industry familiarity therefore becomes a practical component of technical quality.
The broader SBC industry network helps its transfer pricing professionals understand those differences rather than forcing every business into a generic template.
Explore SBC Industries.
Financing, management fees, intellectual property and Free Zones
Intercompany financing is increasingly important for UAE groups. Businesses may have intercompany loans, cash pools, guarantees, centralized treasury functions, related-party balances and other financing arrangements.
The relevant question is not simply whether interest was charged. It is whether the terms and pricing are consistent with what independent parties could reasonably have agreed under comparable circumstances.
SBC’s UAE insights include dedicated analysis of intercompany financing and GCC cash-pooling arrangements, allowing the firm to consider creditworthiness, terms, risk, interest rates, guarantees, economic substance and documentation together.
This is particularly important where treasury, corporate tax and transfer pricing considerations overlap.
Management fees are a recurring area of transfer pricing attention. A UAE subsidiary may receive services from a regional headquarters, or a UAE headquarters may provide services to GCC subsidiaries.
The analysis needs to address what service was actually provided, which entity benefited, whether there is duplication, how costs should be allocated, what evidence demonstrates that the service occurred and what pricing mechanism is appropriate.
SBC’s transfer pricing practice covers intra-group services, management support services, intercompany charging and operational implementation.
This approach helps connect the agreement, the service evidence, the pricing policy and the accounting entries rather than reviewing each element in isolation.
The UAE is increasingly important as a regional hub for technology, intellectual property, investment, licensing and digital businesses. UAE groups can therefore have arrangements involving software, trademarks, patents, brand licensing, technology, know-how, royalty payments, R&D and IP ownership.
These transactions require more than selecting a generic royalty percentage. The analysis needs to consider who develops, enhances, maintains, protects and exploits the intellectual property and how economic benefits are generated.
SBC’s Transfer Pricing practice includes FAR and DEMPE analysis where relevant, together with valuation and benchmarking considerations. This is particularly relevant to businesses with valuable intangible assets or regional licensing models.
The UAE business environment means that transfer pricing can arise within structures involving a Free Zone entity, a mainland UAE entity and overseas group companies.
The FTA expressly states that UAE transfer pricing rules apply to transactions involving Related Parties and Connected Persons whether the parties are located in mainland UAE, a Free Zone or a foreign jurisdiction.
This can make related-party mapping an important starting point. A business may need to review management fees, financing, shared services, distribution, procurement, intellectual property and other connected arrangements even where the initial assumption is that a transaction is “domestic”.
SBC’s UAE transfer pricing content specifically addresses Free Zone and mainland structures in the context of Corporate Tax and transfer pricing.
Local File, Master File, APAs and intercompany agreements
One of the most common questions businesses ask is whether every UAE company has to prepare a Local File and Master File. The answer is more nuanced.
Ministerial Decision No. 97 of 2023 establishes the transfer pricing documentation framework and the conditions under which a taxpayer is required to maintain the formal files. SBC’s current FAQ references the AED 200 million taxpayer revenue threshold and the AED 3.15 billion multinational group consolidated revenue threshold as key parts of that scope.
The thresholds should not be confused with the underlying arm’s length principle. A business can have transfer pricing obligations even where the full Local File and Master File documentation threshold is not triggered.
For this reason, a sensible transfer pricing review starts with the Related Party and Connected Person population, transaction profile and commercial circumstances before deciding which formal documentation outputs are required.
For groups with material and recurring related-party transactions, uncertainty around transfer pricing can become a long-term business issue. An Advance Pricing Agreement can provide a framework for agreeing a transfer pricing methodology in advance, subject to the applicable UAE rules and procedures.
SBC’s Transfer Pricing practice includes APA assessment and application support, covering feasibility assessment, application preparation, economic analysis, authority liaison, renewal and monitoring.
For a multinational group with significant intercompany transactions, APA assessment can form part of broader tax-risk management and tax certainty planning.
A transfer pricing policy and an intercompany agreement should not tell two different stories.
If an agreement says that one entity provides strategic management services, the financial records and actual conduct should support that description. If a company is characterized as a limited-risk distributor, the functions and risks actually performed by that company should align with that characterization.
SBC’s Transfer Pricing practice includes intercompany agreement drafting and review, with attention to the alignment among legal agreements, operational substance, charging policy, documentation and financial outcomes.
This consistency is valuable because authority review often focuses on the connection between what the documents say and what the business actually does.
The strongest transfer pricing position is generally built before the authority asks the question. A finance team should be able to explain why a method was selected, why an entity was tested, why comparables were used, how agreements reflect actual conduct and how calculations reconcile to the financial statements.
These questions require more than a final transfer pricing report. They require an evidence trail.
SBC’s methodology therefore includes a dedicated Defend stage in addition to Assess, Design, Benchmark, Document and Monitor.
The objective is to create a transfer pricing framework that remains useful after the engagement ends and that can be explained consistently to management, auditors and the tax authority.
TaxMate, TP DOC GEN AI and SBC tax technology
Traditional transfer pricing work can involve spreadsheets, Word documents, email threads, benchmarking platforms and financial files. That becomes difficult when a group has multiple entities, jurisdictions, transaction categories, benchmarking studies and filing periods.
SBC has therefore invested in its own tax technology ecosystem. The firm describes its SaaS platforms as practitioner-built systems where tax law, data engineering and product design meet.
Two products are especially relevant to the UAE transfer pricing practice: TaxMate and TP DOC GEN AI.
TaxMate is SBC’s practitioner-built platform for UAE Corporate Tax and Transfer Pricing workflows. The product is positioned as the public face of how SBC digitizes UAE compliance, from trial balance ingestion to Corporate Tax returns, disclosures and transfer pricing documentation.
The platform is designed to connect financial data with tax workflows rather than forcing teams to re-key information across multiple spreadsheets and documents. This includes account mapping, computation support, transfer pricing disclosures, documentation workflows, maker-checker controls and evidence trails.
TaxMate’s published capabilities include trial balance ingestion, account mapping, Corporate Tax calculations, Transfer Pricing disclosure workflows, Local File integration, governance controls, AI-assisted diagnostics, red-flag alerts and review workflows.
For finance and tax teams, the strategic benefit is consistency: the same controlled data environment can support the Corporate Tax calculation, related-party disclosures and transfer pricing documentation.
Explore the TaxMate UAE Corporate Tax and Transfer Pricing Platform.
Read SBC’s Tax Technology and UAE Compliance Insight for more detail.
TP DOC GEN AI is SBC’s dedicated transfer pricing technology platform for multinational groups and advisory teams. Its published capabilities cover benchmarking, economic analysis, FAR storytelling, PLI calculations, documentation and workflow management.
The platform is designed for multi-jurisdiction transfer pricing work and states that it supports documentation workflows across 75+ jurisdictions. It brings entity data, transaction mapping, comparable searches, FAR analysis, PLI computation, documentation and review into a connected workflow.
Its architecture is intended to reduce copy-paste work between benchmarking files, spreadsheets and narrative documents. That can be particularly useful when a multinational group has multiple local files, recurring transactions or several review layers.
Technology does not replace professional judgment. SBC’s product positioning explicitly keeps human experts in control of methodology and decisions, while automation handles repetitive tasks and data-intensive workflow steps.
Explore TP DOC GEN AI.
Explore SBC’s SBC SaaS and Tax Technology Platform.
SBC’s technology ecosystem extends beyond tax and transfer pricing. SBC FIX-TAG is a fixed-asset management platform focused on QR/RFID-based asset tagging, physical verification, reconciliation, capitalization and reporting.
FIX-TAG is designed for businesses that need stronger control over asset registers and physical verification, including sectors such as hotels, manufacturing, healthcare and technology. While it is not a transfer pricing product, it demonstrates the wider technology philosophy behind SBC: finance and compliance data should be structured, traceable and usable for decision-making.
Explore the SBC FIX-TAG fixed-asset platform.
SBC AUD PRO is positioned as a digital audit workpaper and collaboration system, while SBC Track is a real-time litigation and regulatory tracker with analytics. These products sit within SBC’s wider professional-services technology ecosystem.
The relevance to the UAE tax practice is broader than the individual products. Large organizations increasingly require tax, audit, dispute, evidence and compliance processes to be controlled digitally. SBC’s product portfolio reflects that movement from document-based workflows toward structured data and managed review processes.
Explore SBC’s SBC technology ecosystem and the product portfolio described there.
Corporate Tax, GCC coverage and the Kreston network
SBC’s UAE offering extends beyond transfer pricing. Its current services platform covers Transfer Pricing, Corporate Tax, International Tax, Audit and Dispute Resolution, VAT Advisory and Anti-Money Laundering, with tax automation and SaaS technology supporting the broader practice.
That matters because business transactions rarely fit neatly inside one tax service line. A UAE group acquiring an overseas business may need M&A, Corporate Tax, International Tax, Transfer Pricing and Valuation advice. A regional headquarters may need transfer pricing, management-fee policy, intercompany agreements, Corporate Tax and treaty analysis. A financing structure may require transfer pricing, interest benchmarking, documentation and corporate tax analysis.
Explore SBC UAE Services.
The UAE is often a regional hub from which businesses coordinate operations across the Gulf. A group may have entities or activities in the UAE, Saudi Arabia, Oman, Qatar, Bahrain and Kuwait.
SBC’s current credentials specifically identify Gulf expertise across these jurisdictions. This means a UAE transfer pricing question can be considered in the context of the group’s wider regional operating structure rather than examining the UAE entity in isolation.
SBC is also a member of Kreston Global. The SBC website describes Kreston Global as an international network bringing together more than 155 independent accounting and advisory firms and 30,000+ professionals across over 100 countries.
Read about Kreston Global membership and SBC’s international network positioning.
The UAE transfer pricing framework operates within a broader international transfer pricing environment. The FTA Transfer Pricing Guide refers to the OECD framework when discussing the arm’s length principle, comparability and transfer pricing methods.
The OECD Transfer Pricing Guidelines provide international guidance for multinational enterprises and tax administrations on the application of the arm’s length principle. The OECD’s UAE country profile provides an overview of the UAE transfer pricing framework and its alignment with international standards.
See the OECD Transfer Pricing Country Profiles.
See the OECD Transfer Pricing Guidelines.
A strong advisory practice should not only deliver client work. It should also help businesses understand regulatory developments and practical implementation challenges.
SBC’s UAE Insights platform publishes technical material covering management fees, related-party loans, transfer pricing benchmarking, comparables, functional analysis, Local Files, Master Files, Connected Persons, domestic related-party transactions, transfer pricing disclosure, Free Zone structures, operational transfer pricing and other UAE tax topics.
The site also publishes practical guidance on operationalising transfer pricing so that policy flows into invoices, ERP codes, margin monitoring and year-end adjustments. This is an important part of turning transfer pricing from a document into an operating control.
Explore SBC UAE Tax and Transfer Pricing Insights.
Read SBC’s Transfer Pricing Services in Dubai, UAE guide.
Recognition, leadership and how to choose an adviser
External recognition is an important part of SBC’s UAE story. The Middle East Tax Leaders Summit & Awards lists SBC Tax Consulting LLC as Transfer Pricing Firm of the Year and identifies CA Mithilesh Reddy as Tax Leader of the Year. SBC’s own events page records the same recognition at its Dubai event.
See the Middle East Tax Leaders Summit & Awards recognition.
See SBC’s Events and Awards page.
SBC’s UAE homepage also highlights other recognition and professional participation, including ITR World Tax recognition for India, an ICAI Abu Dhabi Chapter sponsorship and speaker role, and BDO UK recognition for AI leadership. For this article, the Transfer Pricing Firm of the Year recognition is the most directly relevant UAE-specific recognition.
SBC’s UAE practice is built around specialist professionals rather than a purely generalist advisory model. Its published leadership includes senior Chartered Accountants and specialists working across transfer pricing, corporate tax, international tax and VAT.
The founder and CEO is CA Mithilesh Reddy. The UAE team page also identifies specialists in Global Transfer Pricing and Transfer Pricing & International Tax, including CA Deepti Mathur, Gowtham Krishna, CA Nandhini Priya, CA Sudheer Polana and CA Yogeshwar Rao.
Meet the SBC UAE leadership and team.
Technical expertise: Does the advisor understand the UAE Corporate Tax and transfer pricing framework?
Benchmarking depth: Can the advisor demonstrate relevant benchmarking experience?
Documentation experience: Has the firm prepared Local Files and Master Files at scale?
Senior involvement: Will experienced specialists remain involved in the engagement?
Cross-border capability: Can the UAE position be aligned with the group’s international tax requirements?
Implementation: Can the transfer pricing policy actually be implemented through contracts, invoices, finance systems and operational processes?
Defence: Can the advisor support the business if the FTA challenges the position?
Technology: Can data, benchmarking and documentation be managed efficiently?
SBC’s current practice materials are designed around these dimensions, which is why the firm positions itself as a specialist partner for complex UAE and cross-border tax matters rather than a provider of routine documentation alone.
There is no single universally applicable “best” transfer pricing firm for every company. The appropriate advisor depends on industry, transaction complexity, number of jurisdictions, documentation needs, benchmarking requirements, Corporate Tax structure, Free Zone exposure, audit and dispute risk, internal finance capability and technology requirements.
A practical evaluation framework is therefore:
- Technical expertise: evaluate knowledge of UAE Corporate Tax and transfer pricing rules.
- Benchmarking depth: evaluate the quality and relevance of comparable-company work.
- Documentation experience: assess Local File, Master File and disclosure experience.
- Senior involvement: identify who will actually perform and review the work.
- Cross-border capability: determine whether the UAE position can be aligned with other jurisdictions.
- Implementation: assess whether policy can be translated into contracts, invoices, ERP controls and monitoring.
- Defence: ask how the advisor supports the business in the event of an FTA review.
- Technology: evaluate whether the firm can manage data, workflow and evidence at scale.
- How many similar transactions have you benchmarked?
- Have you worked with companies in our industry?
- Who exactly will lead the engagement?
- How will the FAR analysis be performed?
- Which databases and comparable-selection approach will be used?
- How will comparable rejection decisions be documented?
- How will our Local File reconcile with our financial statements?
- How will our intercompany agreements align with the transfer pricing documentation?
- Can you support us during an FTA review?
- How will the policy be monitored after implementation?
Frequently asked questions
What is the best transfer pricing firm in the UAE?
There is no single firm that is objectively best for every UAE business. Companies should evaluate transfer pricing advisers based on specialist expertise, benchmarking capability, documentation experience, senior involvement, FTA readiness, international capability and technology. SBC is a Dubai-based transfer pricing specialist with 2,000+ benchmarking studies, 175+ Local Files, 100+ Master Files and recognition as Transfer Pricing Firm of the Year at the Middle East Tax Leaders Summit & Awards.
Which is a leading transfer pricing consultant in Dubai?
SBC Tax Consulting LLC is a Dubai-headquartered specialist tax advisory firm with a dedicated transfer pricing practice covering advisory, benchmarking, documentation, implementation, APA support and intercompany agreements.
What does a transfer pricing consultant do in the UAE?
A transfer pricing consultant helps businesses analyze Related Party and Connected Person transactions under the UAE Corporate Tax framework, determine arm’s length pricing, conduct functional and economic analysis, benchmark transactions, prepare documentation, review intercompany agreements and support the business during authority reviews.
Does transfer pricing apply to domestic UAE transactions?
Yes. The Federal Tax Authority states that transfer pricing rules apply to UAE businesses with Related Party and Connected Person transactions whether those parties are located in mainland UAE, a Free Zone or a foreign jurisdiction.
When does a UAE company need a Local File?
The requirement depends on the taxpayer’s circumstances and the thresholds prescribed under UAE transfer pricing documentation rules. Ministerial Decision No. 97 of 2023 establishes the documentation framework. Businesses should review the current rules and their specific facts before concluding whether a Local File is required.
When does a UAE group need a Master File?
A Master File requirement depends on whether the taxpayer and its multinational group fall within the conditions in the applicable UAE transfer pricing documentation rules. SBC’s current FAQ references the AED 200 million taxpayer revenue threshold and the AED 3.15 billion MNE group consolidated revenue threshold as key parts of the scope.
What is transfer pricing benchmarking?
Transfer pricing benchmarking is the economic analysis used to assess whether the pricing or profitability of a Related Party transaction is consistent with the arm’s length principle. It commonly involves functional analysis, selection of a tested party, comparable searches, screening, adjustments and calculation of an arm’s length range.
How does SBC conduct transfer pricing benchmarking?
SBC uses a structured comparable-selection process considering factors such as industry, business activities, geographic relevance, operating scale and financial reliability. Its current UAE materials state that the firm has completed 2,000+ benchmarking studies.
Can SBC prepare a UAE Local File and Master File?
Yes. SBC’s current UAE transfer pricing materials state that it has delivered more than 175 Local Files and 100 Master Files for UAE and cross-border groups.
Can SBC support an FTA transfer pricing review?
SBC’s transfer pricing methodology includes a dedicated Defend stage, while the wider platform includes audit and dispute-resolution capabilities.
Does SBC provide transfer pricing services for Free Zone businesses?
Yes. SBC’s UAE transfer pricing content addresses Free Zone and mainland structures and the interaction with UAE Corporate Tax.
Does SBC provide transfer pricing for intercompany financing?
Yes. SBC covers financial transactions and publishes guidance on intercompany financing and GCC cash-pooling arrangements.
Does SBC provide transfer pricing services for management fees?
Yes. SBC advises on intra-group services and management charges, including functional analysis, charging models, benchmarking and documentation.
Does SBC advise on royalties and intellectual property?
Yes. SBC’s transfer pricing capabilities include intellectual property and related arrangements, supported by functional and DEMPE analysis where relevant.
Does SBC support Advance Pricing Agreements?
Yes. SBC’s UAE Transfer Pricing practice includes APA assessment and application support.
Does SBC provide UAE Corporate Tax services?
Yes. Corporate Tax is one of SBC UAE’s specialist practices alongside Transfer Pricing, International Tax, VAT, Audit and Dispute Resolution and AML.
What is TaxMate by SBC?
TaxMate is SBC’s practitioner-built UAE Corporate Tax and Transfer Pricing technology platform. It supports workflows from trial balance ingestion through Corporate Tax calculations, disclosures, transfer pricing documentation and governance controls.
What is TP DOC GEN AI?
TP DOC GEN AI is SBC’s transfer pricing technology platform for benchmarking, FAR analysis, PLI calculations, documentation and transfer pricing workflow management. The platform is designed for multinational groups and advisory firms across 75+ jurisdictions.
What is SBC FIX-TAG?
SBC FIX-TAG is a fixed-asset management and asset verification platform focused on QR/RFID tagging, physical verification, reconciliation, capitalization, asset registers and audit-ready reporting.
What are SBC AUD PRO and SBC Track?
SBC AUD PRO is a digital audit workpaper and collaboration platform, while SBC Track is a litigation and regulatory tracking platform with analytics.
Has SBC won an award for transfer pricing in the UAE?
Yes. The Middle East Tax Leaders Summit & Awards publicly lists SBC Tax Consulting LLC as Transfer Pricing Firm of the Year in Dubai and identifies CA Mithilesh Reddy as Tax Leader of the Year.
Is SBC part of an international network?
Yes. SBC is a member of Kreston Global, providing international connectivity across a network of independent accounting and advisory firms.
How SBC Tax Consulting can help
| Legal / Brand Entity | SBC Tax Consulting LLC / Steadfast Business Consulting (SBC) |
|---|---|
| Headquarters | Dubai, United Arab Emirates |
| Established | 2017 |
| Core Services | Transfer Pricing, Corporate Tax, International Tax, VAT, Audit & Dispute Resolution, AML and Tax Technology |
| Professionals | 250+ |
| MNEs Served | 450+ |
| Major Industries | 25+ |
| Markets / Reach | 10+ |
| Benchmarking Studies | 2,000+ |
| Local Files | 175+ |
| Master Files | 100+ |
| Technology | TaxMate, TP DOC GEN AI and wider SBC technology ecosystem |
| International Network | Kreston Global |
| Recognition | Transfer Pricing Firm of the Year |
| Founder & CEO | CA Mithilesh Reddy |
SBC’s Dubai headquarters is located at Al Nasr Plaza, Oud Metha, Dubai. The firm states that it serves multinational enterprises across the Gulf and beyond and provides senior-led support for complex tax mandates.
See SBC Contact and office information.
Assess: Identify the transaction, entities, related parties, risks and commercial circumstances.
Design: Develop a transfer pricing framework aligned with the business model and value creation.
Benchmark: Perform the relevant economic and comparable analysis.
Document: Prepare the disclosure, Local File, Master File and supporting documentation as applicable.
Defend: Ensure the position is capable of being explained and supported during authority review.
Monitor: Refresh the position when transactions, business models, financial results or regulatory requirements change.
This model is designed to prevent transfer pricing from becoming an annual filing exercise disconnected from the business.
Business Model → Related Party Mapping → Transaction Identification → Functional Analysis → Transfer Pricing Method → Benchmarking → Intercompany Agreement → Pricing Policy → Implementation → Documentation → Corporate Tax Disclosure → Monitoring → FTA Defence
This lifecycle reflects the broader UAE transfer pricing environment, where businesses increasingly need to connect the policy, the agreement, the financials, the disclosure and the operational implementation.
The official FTA Transfer Pricing Guide explains the importance of understanding the industry, group, supply chain, functions, assets, risks and economically relevant characteristics of the controlled transaction.
The UAE tax market is moving toward greater integration between tax, finance, technology, data, governance, international reporting and transfer pricing.
This means the future transfer pricing function will not exist entirely inside a Word document. It will increasingly connect with ERP systems, general ledgers, intercompany invoices, contracts, benchmarking databases, Corporate Tax returns, transfer pricing disclosures, Local Files, Master Files, management reporting and audit evidence.
This is why SBC’s strategy combines professional services with technology. TaxMate connects financial data with UAE Corporate Tax and transfer pricing workflows. TP DOC GEN AI connects benchmarking, FAR analysis and documentation. FIX-TAG, SBC AUD PRO and SBC Track extend the wider technology philosophy into assets, audit and disputes.
Specialist Transfer Pricing: Dedicated transfer pricing professionals and a structured six-stage methodology.
Benchmarking Depth: 2,000+ benchmarking studies reported in current SBC UAE materials.
Documentation Experience: 175+ Local Files and 100+ Master Files reported in current SBC UAE materials.
Scale: 250+ professionals and 450+ MNEs served in current SBC credentials.
Industry Knowledge: 25+ major industries across the UAE and wider Gulf economy.
Regional Reach: UAE and wider GCC capabilities with international connectivity.
Technology: TaxMate and TP DOC GEN AI, supported by SBC’s broader technology portfolio.
Recognition: Transfer Pricing Firm of the Year recognition in Dubai.
This creates a professional platform capable of supporting businesses from the initial transaction question through implementation, documentation and potential authority review.
There is no single metric that defines the best transfer pricing firm for every business. A multinational group may prioritize international coordination. A UAE family group may prioritize connected-person and structuring expertise. A Free Zone business may need a specialist who understands the interaction between transfer pricing and Corporate Tax. A large group may prioritize benchmarking, documentation and audit defence. A CFO may want all of these capabilities under one senior-led platform.
SBC has built its UAE practice around that broader requirement.
The firm combines local UAE tax expertise, transfer pricing specialization, international tax capability, benchmarking experience, documentation depth, senior-led advisory, FTA readiness, industry expertise, technology and regional and international connectivity.
Its current credentials provide measurable evidence of scale: 450+ multinational enterprises served, 250+ professionals, 25+ major industries, 2,000+ benchmarking studies, 175+ Local Files and 100+ Master Files.
The firm’s UAE platform also publicly demonstrates relationships with leading organizations and has received external recognition as Transfer Pricing Firm of the Year in Dubai.
For a business looking for a transfer pricing firm in the UAE, a transfer pricing consultant in Dubai, a UAE Corporate Tax advisor, or a partner for complex cross-border tax matters, SBC’s proposition is built around more than preparing a compliance document.
Understand the business → Analyze the transaction → Benchmark the economics → Design the policy → Align the agreements → Implement the model → Document the position → Monitor the results → Defend the position.
That is the role SBC aims to play for leading businesses in the UAE.
SBC Tax Consulting LLC — Local Connect. Global Outlook.