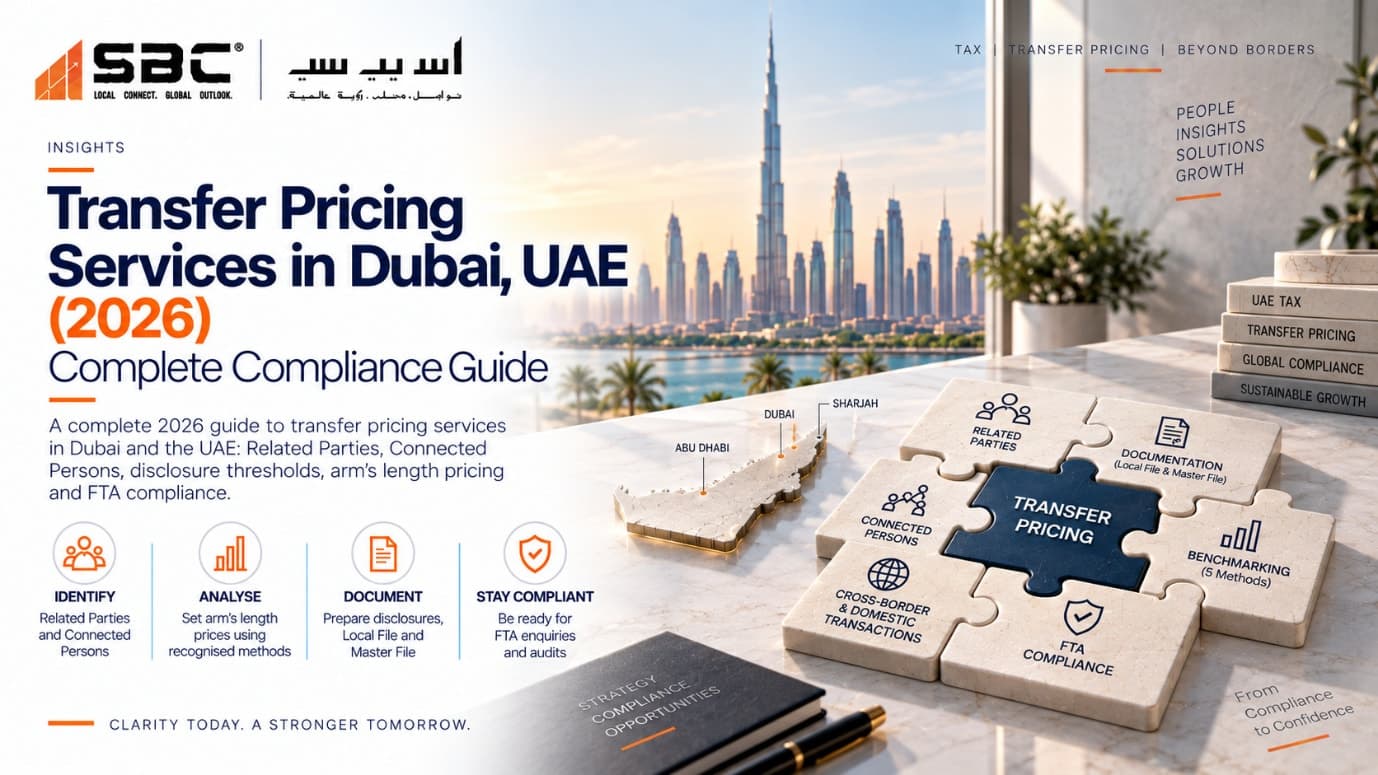
If a UAE business transacts with a Related Party, or makes a payment or provides a benefit to a Connected Person, UAE transfer pricing rules can apply whether the other party is in Dubai, another Emirate, a UAE Free Zone or another country. Article 34 of the Corporate Tax Law contains the arm's length principle, Article 35 identifies Related Parties, Article 36 deals with Connected Persons, and Article 55 governs transfer pricing documentation. The rules are not limited to multinationals or cross-border transactions.
This guide is written for the finance controller, CFO, tax head, group finance director, owner-manager or promoter of a UAE business that buys from, sells to, lends to, borrows from, provides services to, receives services from, licenses intellectual property to, or otherwise transacts with another member of the same group - or pays an owner, director or other Connected Person a salary, fee or benefit that has to be justified for Corporate Tax purposes.
The UAE tax system is distinctive because it contains mainland businesses, Free Zone businesses, Qualifying Free Zone Persons, regional headquarters, holding companies, distribution businesses, service centres and cross-border financing structures side by side. A transaction can be entirely domestic - Dubai to Abu Dhabi, mainland to Free Zone - and still create a transfer pricing question. How to shortlist an adviser is covered in Best Transfer Pricing Firm in UAE. The mechanics of benchmarking, Local File and Master File sit in the companion guide.
What do transfer pricing services in Dubai actually cover?
Transfer pricing services in Dubai and across the UAE cover considerably more than a benchmarking report produced once a year.
Impact assessment and transaction mapping identifies Related Parties and Connected Persons, maps general-ledger transactions, and determines which dealings fall within Corporate Tax disclosure. See how to identify Related Parties and Connected Persons.
Price setting and benchmarking uses the five recognised methods - Comparable Uncontrolled Price, Resale Price, Cost Plus, Transactional Net Margin, and Profit Split - to determine what a UAE entity should earn or pay.
Compliance documentation covers the Related Party and Connected Person disclosures forming part of the Corporate Tax Return, together with the Local File and Master File where thresholds are met.
Operational transfer pricing makes sure intercompany agreements, invoices, cost allocations, loan terms and accounting entries tell the same story as the benchmarking report. See from policy to invoice.
Controversy and certainty covers responding to FTA enquiries, defending the economic analysis, and considering an Advance Pricing Agreement for material, recurring controlled transactions.
What transfer pricing obligations does a UAE company actually carry?
The starting point is not turnover - it is the relationship and the transaction. The AED 200 million and AED 3.15 billion figures are documentation thresholds; they are not a general exemption from the arm's length principle.
| Requirement | UAE provision / guidance | Practical effect |
|---|---|---|
| Arm's length principle | Article 34 | Related Party transactions priced as between independent parties |
| Related Party determination | Article 35 | Relationships arising through ownership, control and prescribed relationships |
| Connected Person payments | Article 36 | Deduction restricted by reference to Market Value / arm's length conditions |
| TP disclosure | Article 55(1) and the Corporate Tax Return Guide | Certain Related Party and Connected Person transactions are disclosed with the Corporate Tax Return |
| Master File and Local File | Article 55 and Ministerial Decision No. 97 of 2023 | Required once prescribed revenue or group thresholds are met |
| Submission of TP documentation | Article 55 | Master File / Local File requested by the FTA, generally within 30 days |
| Advance Pricing Agreement | Article 59 and the FTA APA Guide | Prospective certainty for qualifying controlled transactions |
Who is in scope, and which dealings Article 34 actually covers, is set out in UAE transfer pricing rules: who is covered.
Does UAE transfer pricing apply only to transactions with foreign companies?
No - and this is one of the most important gaps between how many businesses initially understand UAE transfer pricing and how the legislation actually operates. The FTA confirms that transfer pricing rules apply to transactions with Related Parties and Connected Persons whether they are situated in the UAE mainland, a Free Zone, or outside the UAE.
A Dubai company purchasing from its Abu Dhabi sister company can have a transfer pricing issue. A mainland company providing services to its Free Zone Related Party can have one. A Free Zone company paying a management fee to another UAE group company can have one. And a company paying remuneration to its shareholder-director may have a Connected Person issue even though no overseas entity is involved. A review that begins only with the foreign Related Party ledger is incomplete. Domestic dealings are covered in more detail in Do domestic related-party transactions need transfer pricing in the UAE?.
What has to be disclosed in the UAE Corporate Tax Return?
Under the FTA's Corporate Tax Returns Guide, the Related Party transaction schedule is triggered where the aggregate value of transactions with all Related Parties exceeds AED 40 million during the Tax Period. Once crossed, categories exceeding AED 4 million must be reported. The Connected Person schedule applies separately once aggregate transactions with Connected Persons exceed AED 500,000. These are disclosure thresholds - not permission to price smaller transactions otherwise than at arm's length.
A practical walkthrough of the two schedules is in UAE Transfer Pricing Disclosure Form: a step-by-step guide.
Does Small Business Relief remove transfer pricing altogether?
No. A business benefiting from Small Business Relief is not required to maintain the prescribed transfer pricing documentation, but it must still comply with the arm's length principle. Relief from the documentation requirement is not relief from the pricing standard itself - proportionate documentation remains useful even below the full Local File threshold where Related Party amounts are commercially significant.
Penalties and audit risk: why transfer pricing errors compound quickly
There is no separate transfer-pricing-specific penalty regime in the UAE - TP failures fall under the Corporate Tax Law's general administrative penalty framework. But the consequences compound: adjusted taxable income, back-dated assessments across multiple financial years, potential loss of Qualifying Free Zone Person status, and closer FTA scrutiny of future filings. A proactive review before filing is materially cheaper than an FTA audit response after the fact.
How does transfer pricing connect with UAE Corporate Tax more broadly?
Transfer pricing should not be treated as a separate report produced after the Corporate Tax computation. Related Party pricing can affect revenue, deductible expenses, financing costs, taxable margins, Free Zone positions and the values disclosed in the Corporate Tax Return.
The FTA's Corporate Tax guidance expressly identifies adjustments for transactions with Related Parties and Connected Persons among the adjustments potentially required in moving from accounting profit to Taxable Income - which is why transfer pricing, Corporate Tax compliance and financial reporting should be reviewed together, not as three independent workstreams.
For the benchmarking mechanics, Local File and Master File thresholds, Free Zone interaction, and intercompany loan and management-fee pricing, see Transfer Pricing Benchmarking, Local File and Master File in the UAE.
What should a UAE company do before filing its Corporate Tax Return?
Do not leave transfer pricing until the disclosure schedule appears on the return. The cleaner process starts from the ledger:
-
Identify Related Parties and Connected Persons across all UAE and foreign group entities.
-
Reconcile each category of controlled transaction against the general ledger.
-
Determine the applicable pricing method and test the result against comparable evidence.
-
Identify any required year-end adjustment before the accounts are finalised.
-
Verify that intercompany agreements match what actually happened operationally.
-
Make sure the amounts in the Corporate Tax Return agree with the supporting transfer pricing file.
For a calendar-year company whose Tax Period ended on 31 December 2025, the Corporate Tax Return and payment are due by the end of September 2026, reflecting the general nine-month filing period. A transfer pricing report completed after the return has already been filed can only explain a number. A review completed before filing can still change it.
Frequently asked questions
Does transfer pricing apply to a small company in Dubai?
Potentially, yes. The arm's length principle is not limited to businesses exceeding the AED 200 million Local File threshold. A smaller UAE business can still have Related Party or Connected Person transactions that need to be priced at arm's length. Businesses qualifying for Small Business Relief are relieved from specified TP documentation requirements but must still comply with the arm's length principle.
Does UAE transfer pricing apply only to international transactions?
No. UAE transfer pricing applies to relevant domestic and cross-border transactions. The counterparty can be in mainland UAE, a Free Zone, or outside the UAE entirely.
What is the UAE transfer pricing disclosure threshold?
For the Related Party schedule, the current FTA Corporate Tax Returns Guide uses an aggregate threshold of more than AED 40 million, after which transaction categories exceeding AED 4 million become reportable. The Connected Person schedule uses a separate AED 500,000 framework.
What is the threshold for a UAE Local File and Master File?
Generally required where the UAE Taxable Person's revenue is at least AED 200 million, or the Taxable Person belongs to an MNE group with consolidated revenue of at least AED 3.15 billion, subject to the detailed rules in Ministerial Decision No. 97 of 2023.
Does a shareholder's salary need transfer pricing support?
It can. Article 36 limits the deductibility of payments or benefits provided to Connected Persons by reference to Market Value and the business-purpose requirement. The FTA specifically refers to an owner's salary as an example.
How does transfer pricing connect with UAE Corporate Tax?
Related Party and Connected Person pricing feeds directly into the Corporate Tax computation - affecting revenue, deductible expenses and taxable margins - so transfer pricing, Corporate Tax compliance and financial reporting should be reviewed as one process, not three.
Are Advance Pricing Agreements available in the UAE?
Yes. The UAE APA programme is operational under Article 59, with FTA guidance explaining unilateral and bilateral APAs, with submissions accepted from 30 December 2025.
Primary sources and further reading
-
Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses
-
Transfer Pricing Benchmarking, Local File and Master File in the UAE
How SBC Tax Consulting can help
SBC's transfer pricing team maps Related Parties and Connected Persons, tests prices before the return is locked, and prepares disclosure, Local File and Master File evidence that matches the ledger. Corporate Tax and international tax sit in the same review so the computation and the TP file do not drift apart. Contact SBC before the next Corporate Tax filing or documentation deadline.
This publication is for general information only and does not constitute professional advice. Please consult your SBC advisor before acting on any matter covered here.