AI in Transfer Pricing UAE: How AI Is Transforming Transfer Pricing Analysis
Introduction: From Manual Benchmarking to Technology-Assisted Transfer Pricing
Transfer pricing has always required more than selecting a percentage, preparing a spreadsheet or producing a report. A defensible analysis requires a clear understanding of the commercial transaction, the functions performed by each party, the assets used, the risks assumed, the economic evidence available and the applicable tax rules.
For multinational enterprises and UAE businesses dealing with related parties, this work can become demanding. Finance and tax teams may need to reconcile information from several entities, review intercompany agreements, analyse financial statements, identify comparable companies, document the functional analysis and explain why the selected pricing method is appropriate.
Artificial intelligence (AI) is creating new possibilities for completing parts of this work more efficiently. It can assist with processing information, organising financial data, identifying patterns, supporting comparable-company research and generating structured documentation. The opportunity is not simply to produce reports faster; it is to improve the connection between source data, economic analysis, professional judgement and final documentation.
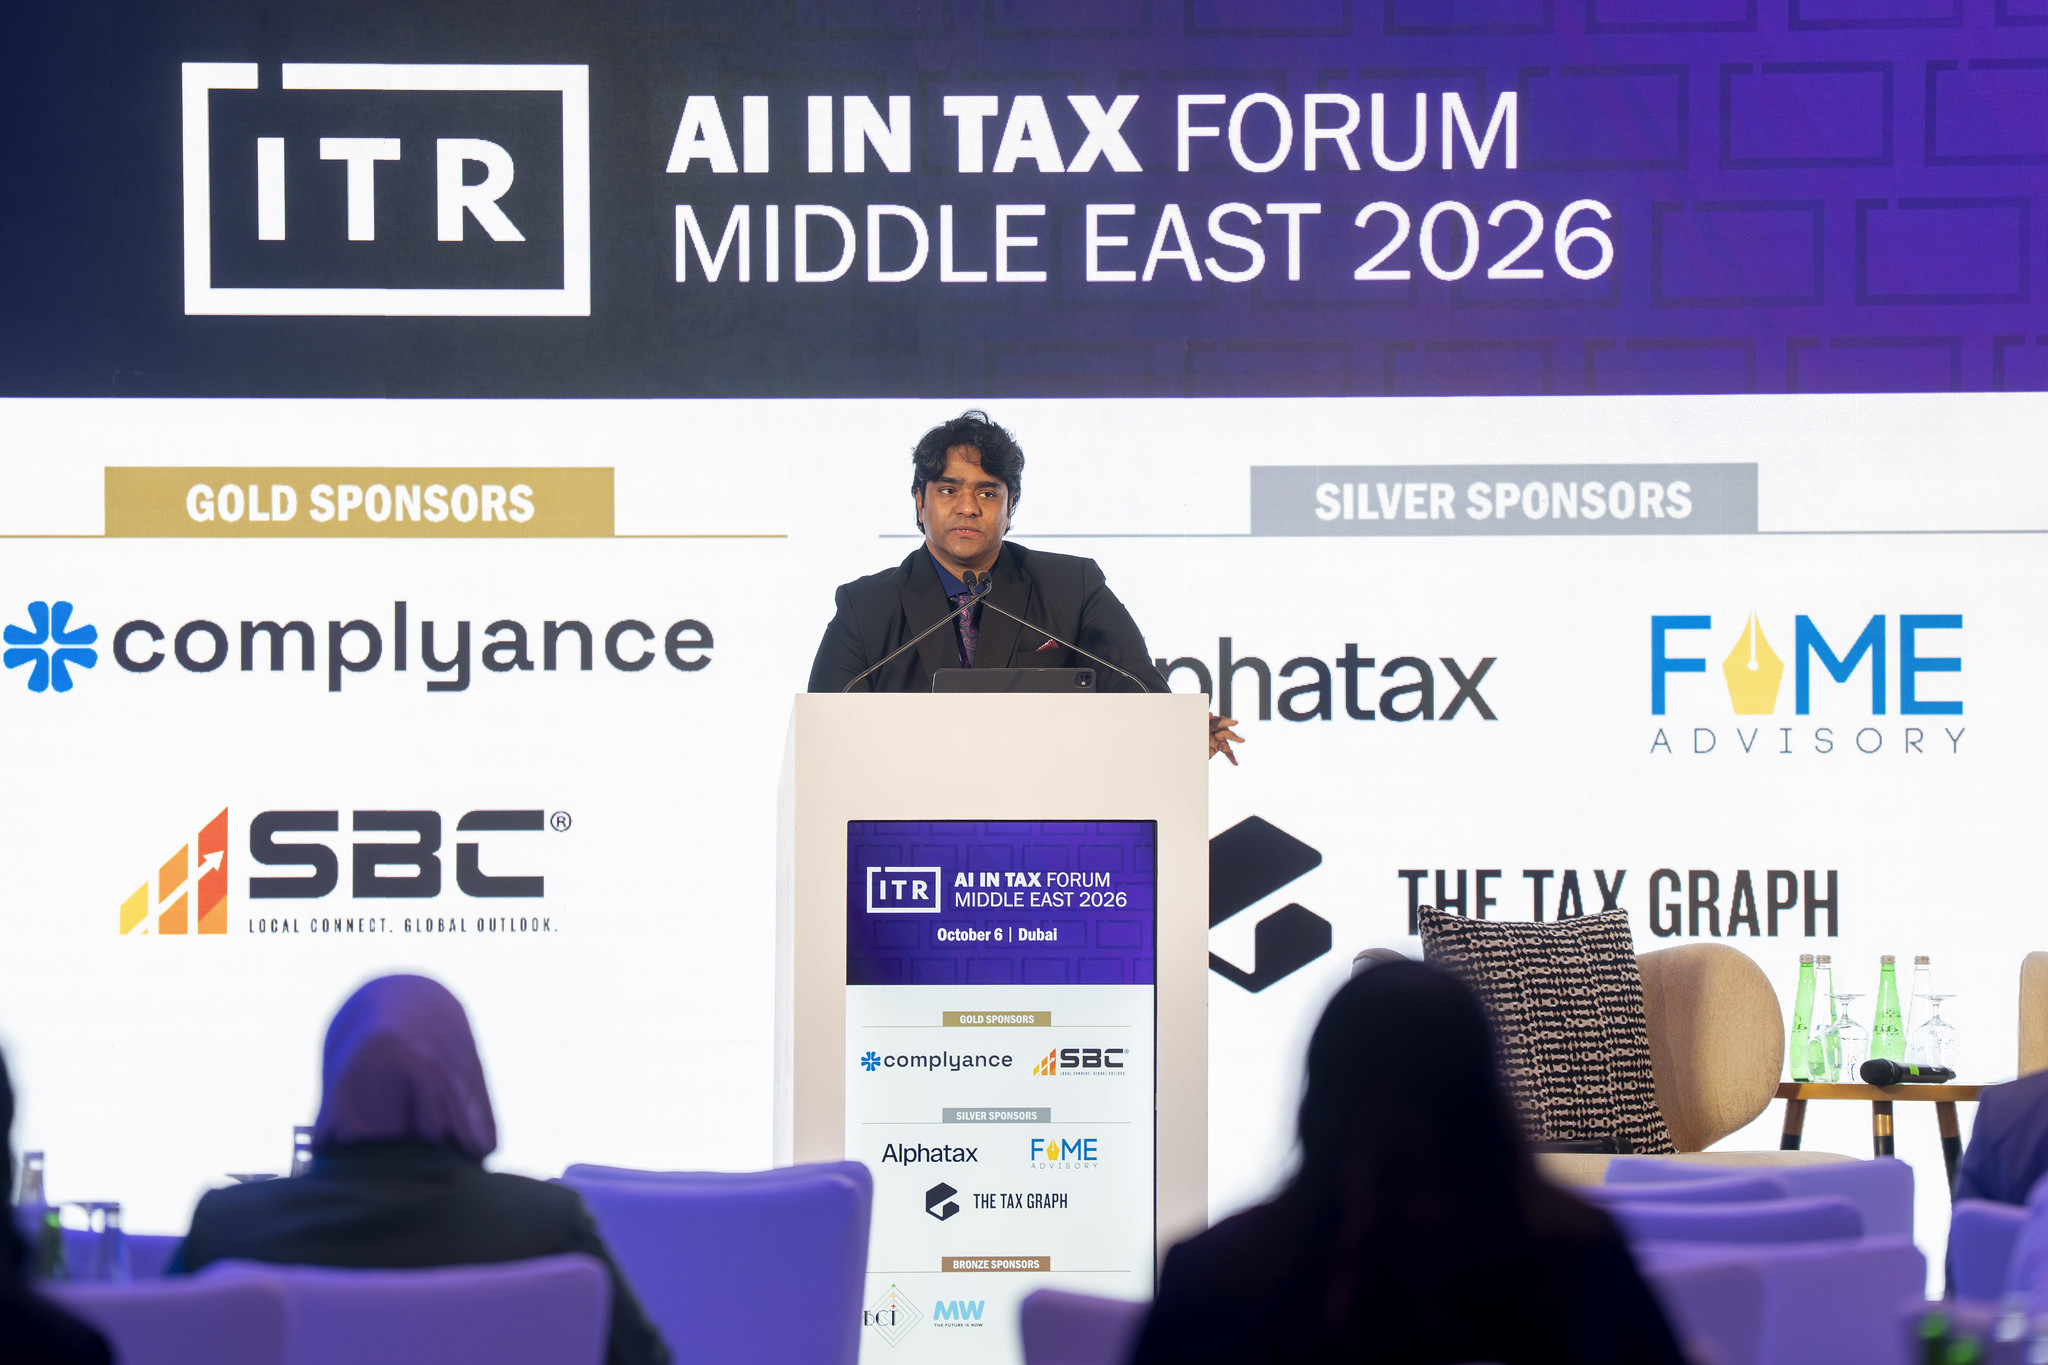
SBC Tax Consulting LLC participated as a Gold Sponsor at the ITR AI in Tax Forum Middle East 2026 in Dubai. During the forum, CA Mithilesh Reddy presented TP DOC GEN AI through a live benchmarking demonstration, showing how AI-enabled workflows can support the speed and execution of transfer pricing analysis.
Read the original SBC LinkedIn event announcement for the event context and demonstration reference. To learn about the platform, visit TP DOC GEN AI.
The practical question is how technology can reduce repetitive work while preserving the analytical quality, accountability and professional review that transfer pricing requires. For SBC, the answer lies in combining specialist transfer pricing knowledge with technology designed around the actual work of tax and finance teams.
What Is AI-Powered Transfer Pricing Analysis?
AI-powered transfer pricing analysis is the use of artificial intelligence and related automation technologies to support activities such as transaction analysis, functional analysis, comparable-company research, economic benchmarking and transfer pricing documentation.
Traditional workflows often involve disconnected tools. A team may collect information through email, extract figures from financial statements, maintain calculations in spreadsheets, prepare functional analysis documents separately and then transfer conclusions into a report. An AI-assisted workflow can connect more of these activities. Depending on the system and controls, it may help organise source information, identify inconsistencies, assist with research, draft analytical narratives and structure outputs for professional review.
The distinction between assistance and decision-making is important. AI does not automatically establish whether a transaction is at arm's length. Nor does an AI-generated report, by itself, demonstrate compliance with tax legislation. The underlying economic analysis must be appropriate for the transaction, supported by reliable evidence and reviewed against the relevant legal framework.
The OECD Transfer Pricing Guidelines provide an important international reference for applying the arm's-length principle to transactions between associated enterprises. AI should help professionals perform the work more effectively, not remove the need for professional judgement.
Why Are Transfer Pricing Teams Exploring AI?
1. Large Volumes of Fragmented Information
A transfer pricing study may require financial statements, trial balances, intercompany agreements, organisation charts, transaction schedules, management explanations and prior-year documentation. These records are often held in different formats and systems.
AI-assisted tools can help extract and organise information, identify missing fields and highlight inconsistencies for review. This can reduce manual effort before substantive analysis begins.
The quality of the result depends on the quality of the source information. Incorrect entity names, incomplete transaction records or outdated financial data can lead to misleading outputs if they are not detected.
2. Comparable-Company Research and Benchmarking
Benchmarking is one of the most resource-intensive elements of many transfer pricing assignments. The analyst must understand the tested party, select an appropriate method, identify suitable comparables, apply screening criteria and assess the resulting financial indicators.
Technology can help structure screening criteria, organise candidate companies, compare financial information and document reasons for including or excluding candidates.
The final selection still requires economic judgement. Two companies operating in the same industry may have materially different functions, assets, risks, geographic exposure or business models. A superficial similarity in business descriptions is not enough to establish comparability.
3. Repeated Documentation Work
Transfer pricing teams often repeat administrative tasks across entities and reporting periods, including collecting standard information, preparing entity descriptions, reconciling figures, updating tables and transferring approved conclusions into reports.
A well-designed workflow can reduce repetition and allow professionals to spend more time on transaction-specific analysis.
4. Inconsistent Data Across the Tax Function
Transfer pricing does not operate in isolation. Related-party transactions affect accounting records, corporate tax computations and, for in-scope multinational groups, global minimum-tax calculations.
When each function uses separate data sources, reconciliation becomes difficult. A connected process can help teams identify differences earlier and establish clearer links between transactions, accounting records and tax reporting.
5. The Need for Traceability
A useful transfer pricing conclusion should be explainable. The analyst should be able to identify the information relied upon, the methodology applied, the assumptions made and the reasoning behind important decisions.
AI systems should therefore be assessed not only on speed but also on transparency, version control, source traceability and the ability of a reviewer to challenge an output.
How AI Can Improve Transfer Pricing Benchmarking
Benchmarking is a useful example of where technology can support a specialist analytical process. It is not simply a search for companies with similar names. The analyst must understand the transaction and identify economically relevant comparables under the chosen transfer pricing method.
Step 1: Define the Transaction and the Tested Party
Before any search begins, the analyst must understand what is being priced. The transaction may involve distribution, manufacturing, management services, financing, licensing of intellectual property or another controlled transaction.
The analysis should establish which entity is being tested, what activities it performs, what assets it uses and which risks it assumes or controls. AI can help organise this information and flag incomplete responses, but it should not substitute a generic business description for a proper functional analysis.
Step 2: Establish the Screening Criteria
The screening criteria should follow the transaction and the selected methodology. Relevant considerations may include business activity, geographic market, operating model, financial data availability, ownership structure and the period being analysed.
Technology can help apply consistent filters and present candidate companies for assessment. The analyst must still determine whether those filters are appropriate.
Step 3: Review Comparable Candidates
AI-assisted tools can organise candidate-company information and draw attention to potentially relevant differences. Reviewers should examine the substance of the business rather than rely exclusively on automated classifications.
A company with a similar industry code may perform different functions or bear materially different risks.
Step 4: Analyse the Financial Indicators
Depending on the method selected, the study may involve gross margins, operating margins, mark-ups or other relevant financial indicators. The analyst should verify the underlying data, calculation periods, adjustments and consistency of financial measures.
Automation can support calculations and highlight unusual values, but it should not conceal formulas or make reconciliation difficult.
Step 5: Document the Reasoning
The benchmarking file should explain how the search was conducted, why selected companies were considered comparable, why other candidates were rejected and how the final range was derived. This reasoning is as important as the numerical result.
Explore the TP DOC GEN AI benchmarking engine for a product-specific view of technology-assisted benchmarking.
For UAE regulatory context, consult the Federal Tax Authority Transfer Pricing Guide, which addresses the local application of transfer pricing principles, comparability analysis and documentation.
What Is TP DOC GEN AI?
TP DOC GEN AI is SBC's AI-powered transfer pricing technology platform, developed around documentation and economic-analysis requirements faced by multinational enterprises and advisory teams. Its public product information describes workflows covering entity onboarding, benchmarking, economic analysis and transfer pricing documentation.
The platform can be explored through the official TP DOC GEN AI website. The live demonstration at the ITR AI in Tax Forum Middle East 2026 focused on benchmarking and illustrated how AI can support the execution of transfer pricing analysis.
The product's public materials describe a benchmarking process in which stages have separate outputs that can be opened and checked. Businesses should review the current product documentation and suitability for their own requirements before adoption.
For documentation workflows, see TP DOC GEN AI Living Documents, which describes editing a transfer pricing report and generating PDF and Word outputs from a common source. This can help reduce discrepancies between a report and its annexures, provided the underlying inputs and approved conclusions are correct.
For source-document processing, see AI document reading. For functional analysis support, see FAR analysis. Capabilities should be assessed against the business's actual data, controls and transaction types.
From Benchmarking to Documentation: Connecting the Transfer Pricing Workflow
Entity and Transaction Onboarding
The team gathers entity details, ownership information, business activities, transaction types, relevant agreements and financial information. Structured onboarding can reduce repeated requests and help identify gaps before the analysis progresses.
Functional Analysis
The analyst evaluates the functions performed, assets used and risks assumed by each party. AI can assist in organising information and preparing a first draft of the narrative, but the description must be checked against actual business conduct and evidence.
Method Selection and Economic Analysis
The appropriate transfer pricing method depends on the facts and circumstances of the transaction. The analyst should consider the nature of the transaction, availability of reliable information and relative strengths and weaknesses of available methods.
AI can support preparation and organisation, but should not select a method without adequate consideration of the facts.
Benchmarking and Calculations
The team conducts the relevant search, applies screening criteria, reviews comparables and verifies calculations. Automation can reduce repetitive steps, while the reviewer remains responsible for the analytical conclusion.
Documentation Generation and Sign-Off
Approved facts, methodology, calculations and conclusions are assembled into the required documentation. The output must be checked for accuracy, consistency and completeness before finalisation.
The responsible professional should resolve exceptions and approve the final output, recording material changes and review comments where appropriate.
SBC also publishes guidance on building a transfer pricing policy for a UAE group. A policy should connect the economic analysis to actual intercompany arrangements and business conduct rather than operate as a standalone document.
Why UAE Businesses Should Pay Attention to AI in Transfer Pricing
The UAE Corporate Tax framework makes transfer pricing relevant to businesses that transact with related parties and connected persons. It is not reserved exclusively for large multinational groups or cross-border transactions. The specific rules and documentation requirements depend on the law, applicable decisions and the facts of the business.
The UAE Federal Tax Authority's Corporate Tax FAQs address the application of Corporate Tax and transfer pricing rules. The UAE Ministry of Finance also publishes information on the Corporate Tax framework and relevant ministerial decisions.
1. Better Organisation of Related-Party Information
Businesses may have transactions involving goods, services, financing, management fees, royalties or other arrangements. An AI-assisted process can help organise transaction information and highlight missing records.
The underlying data should still be reconciled to accounting records and supported by appropriate agreements and evidence.
2. More Consistent Documentation
Where a group has several UAE entities, a structured workflow can help maintain consistency in how facts, calculations and supporting information are collected.
Consistency should not mean using identical narratives for entities with different functions or risks. Each analysis must reflect the relevant entity and transaction.
3. Earlier Identification of Issues
Technology can flag unusual margins, incomplete fields, inconsistent transaction descriptions or differences between source records and draft documentation.
These alerts are indicators for review, not automatic conclusions that a tax error or non-compliance exists.
4. Improved Coordination Across Tax Processes
Transfer pricing can connect with corporate tax, VAT, Pillar Two and e-invoicing because the workstreams may use overlapping transaction and accounting information. The legal requirements differ.
A connected data process can help teams reconcile information, but it does not remove the need to apply the specific rules relevant to each regime.
For more context on the interaction between profit allocation and the global minimum tax, see SBC's guide to UAE Pillar Two and transfer pricing.
AI Does Not Replace the Arm's-Length Principle
Technology does not change the underlying transfer pricing standard. A price does not become arm's length simply because an algorithm produces it or because a report has been generated automatically.
The analyst must evaluate the transaction, economically relevant characteristics, functions performed, assets used, risks assumed and available comparable evidence.
Consider a UAE distributor that purchases goods from an overseas group company. An AI tool may identify candidate comparable distributors and calculate operating margins. The conclusion could still be unreliable if the selected companies operate in materially different markets, perform different functions or assume different inventory and market risks.
The calculations may be correct while the underlying analysis is inappropriate.
The international framework is described in the OECD's transfer pricing resources. For UAE-specific issues, businesses should refer to official local guidance and assess their own facts.
See also SBC's article on which businesses and transactions are covered by UAE transfer pricing rules.
Professional review must be built into the workflow from the beginning rather than added as a final formality.
Human Oversight, Data Governance and Responsible AI
AI adoption in tax and transfer pricing should be accompanied by controls appropriate to the sensitivity of the information and the consequences of an incorrect conclusion.
The NIST AI Risk Management Framework is a useful general reference for thinking about AI risk management, although it is not a substitute for UAE tax legislation.
Data Confidentiality
Transfer pricing files may contain financial statements, commercial agreements, employee information, pricing arrangements and details of group operations. Businesses should understand where data is processed, who can access it, how it is retained and whether it is used to train external models.
Sensitive information should not be uploaded to an AI service unless the use is permitted and appropriate safeguards are in place.
Accuracy and Source Verification
AI-generated summaries and narratives can contain omissions or incorrect interpretations. Financial data, legal references, comparable-company information and regulatory statements must be verified against reliable sources.
Explainability and Traceability
Reviewers should be able to understand the evidence behind material conclusions. A useful system should preserve the connection between source records, calculations, edits and approved outputs.
Approval Controls and Monitoring
The person who prepares or reviews an analysis should have clearly defined responsibilities. Material conclusions should not be accepted solely because a system generated them.
Organisations should periodically test whether the workflow produces reliable outputs and whether controls remain suitable.
A Practical Example: AI-Assisted Benchmarking for a UAE Service Company
Consider a hypothetical UAE company that provides regional management support to other group entities. The finance team has accounting records, an intercompany services agreement, cost schedules and information about activities performed. The records are available, but spread across several files. The team needs a functional analysis and benchmarking study.
An AI-assisted workflow could support the process through the following steps:
-
Organise the information. The team loads approved source documents into a controlled workflow and checks extracted entity details, transaction values and financial information.
-
Prepare a functional-analysis draft. The system helps organise information about activities, assets and risks. The analyst verifies that the narrative reflects actual operations.
-
Define the benchmarking approach. The analyst determines the relevant method and criteria for identifying potentially comparable service providers.
-
Review comparable candidates. The system helps organise candidate information and screening results. The analyst evaluates business models, functions and financial data before deciding which companies are suitable.
-
Verify the financial analysis. The team checks calculations, reporting periods, exclusions and adjustments applied to the data.
-
Prepare the documentation. Approved facts and analysis are assembled into a structured report. The reviewer checks the reasoning, supporting evidence and consistency of conclusions.
The benefit is not that AI independently decides what the company should earn. The benefit is that the team may spend less time on repetitive preparation and more time evaluating whether the analysis is economically sound.
This example is illustrative; the appropriate method, comparables and outcome depend on the actual facts, reliable data and applicable rules.
How CFOs and Tax Leaders Should Evaluate Transfer Pricing AI
A decision to adopt AI should be based on the quality of the workflow, not the novelty of the technology. Before implementation, CFOs, tax directors and finance leaders should ask:
-
Does the tool address a real bottleneck? Identify whether the main difficulty lies in data collection, benchmarking, documentation, review or coordination.
-
Can it handle the relevant transaction types? Consider the business models and jurisdictions involved.
-
Are the outputs explainable? The team should be able to review the data, methodology, calculations and reasoning behind material conclusions.
-
Can the organisation retain control? Users should be able to challenge, correct and approve outputs under the organisation's review process.
-
Does it support the required documentation? The final deliverables must meet applicable requirements and accurately reflect the underlying analysis.
-
Are confidentiality and access controls adequate? Assess data handling, permissions, retention and security before introducing sensitive records.
-
Can the workflow integrate into existing processes? The objective should be to reduce fragmentation, not create another disconnected tool.
-
How will performance be measured? Useful measures may include preparation time, correction rates, completeness of source data, reviewer effort and the frequency of detected inconsistencies. These should be measured rather than assumed.
A pilot involving a defined transaction type can help an organisation test these questions before wider adoption. The review should consider output quality as well as speed.
SBC's Participation at the ITR AI in Tax Forum Middle East 2026
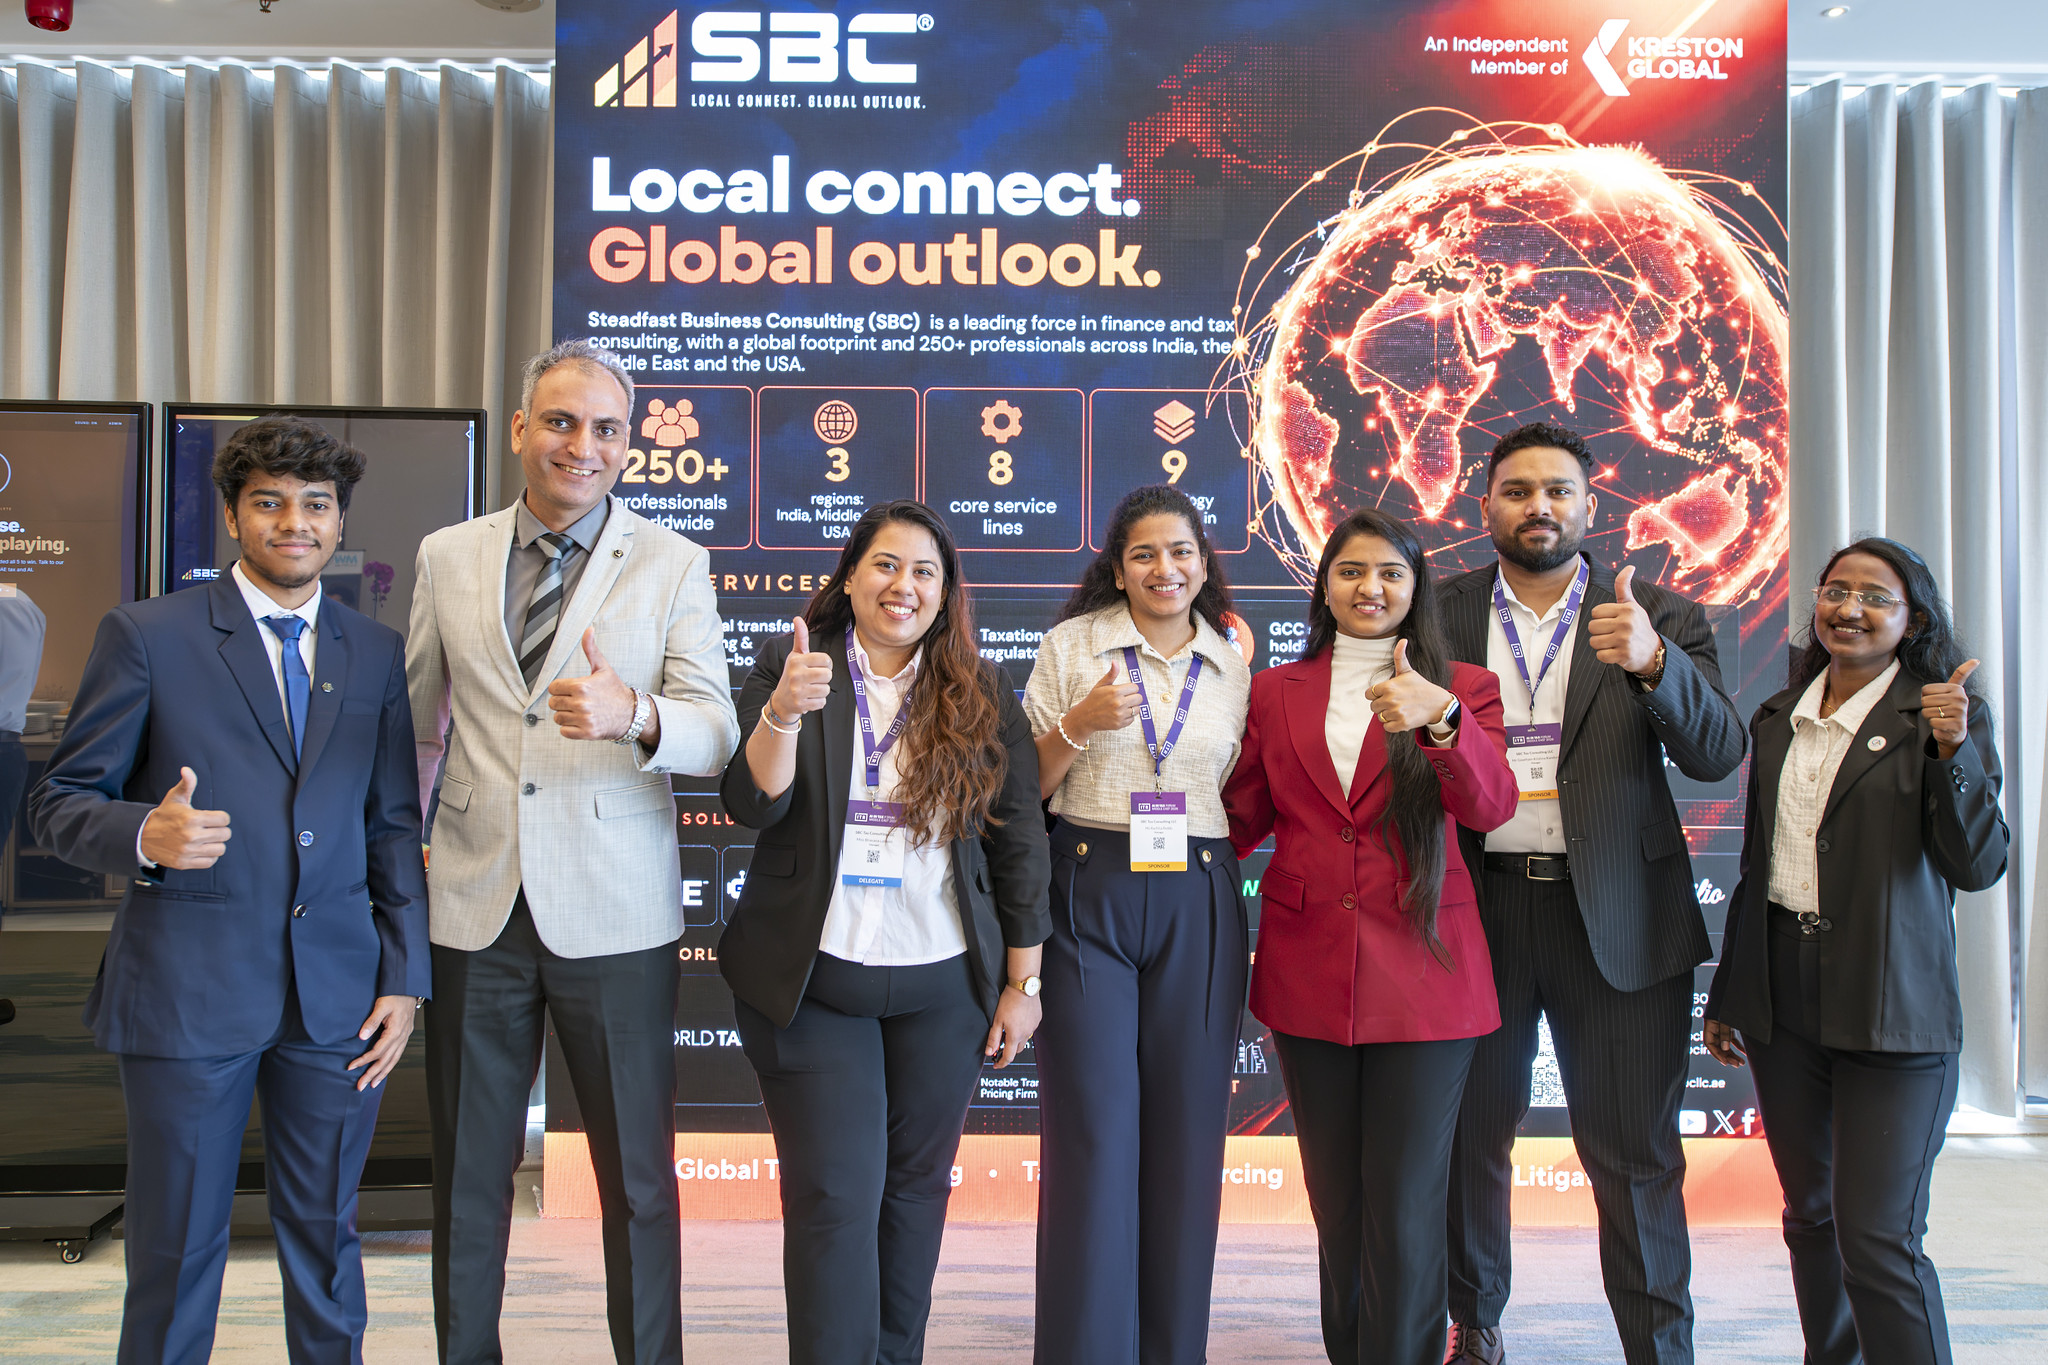
SBC Tax Consulting LLC participated as a Gold Sponsor at the ITR AI in Tax Forum Middle East 2026 in Dubai. During the event, CA Mithilesh Reddy presented TP DOC GEN AI through a live benchmarking demonstration.
The demonstration placed transfer pricing technology in a practical professional context: AI can support the execution of analytical work, while the quality of the conclusion continues to depend on the underlying facts, methodology and review.
SBC also showcased a portfolio of 13 technology intangibles spanning tax technology, indirect tax and e-invoicing, finance and audit, and governance and practice management. The LinkedIn announcement described a shared AI layer connecting these capabilities, with human review and sign-off remaining central.
This broader perspective matters because tax processes increasingly depend on connected information. Transfer pricing conclusions may need to reconcile with corporate tax reporting, accounting data and other compliance processes. Technology is most useful when it helps professionals maintain those connections without obscuring the reasoning behind the final result.
Read the original LinkedIn post from SBC for the event announcement and related product information.
Explore the TP DOC GEN AI platform to learn more about its transfer pricing workflows, and visit SBC LLC UAE for the firm's tax and transfer pricing advisory insights.
Where AI Fits into the Future of Transfer Pricing
AI is likely to become an increasingly important part of the transfer pricing technology landscape. The most useful applications will address identifiable problems, produce verifiable outputs and fit into a well-governed professional process.
For UAE businesses, the immediate opportunity is practical rather than theoretical. Organisations can review how they collect related-party data, conduct benchmarking, prepare documentation and coordinate tax information across systems. They can then determine where automation is appropriate and where specialist judgement remains essential.
The direction of travel is toward more connected workflows, clearer data trails and better use of professional time. Achieving these outcomes requires more than purchasing software. It requires suitable data, defined responsibilities, appropriate review procedures and a clear understanding of the applicable tax rules.
SBC's demonstration of TP DOC GEN AI at the ITR AI in Tax Forum Middle East 2026 reflected this approach: technology can change how transfer pricing work is executed, but sound analysis and human accountability remain fundamental.
For tax leaders, the useful question is not simply whether AI can generate a transfer pricing report. It is whether the process, from source information and benchmarking to review and final documentation, can become more efficient, consistent and defensible.
Businesses considering their next steps can explore SBC's UAE transfer pricing services and compliance guidance and the TP DOC GEN AI product website.
Frequently Asked Questions (FAQs)
1. What Is AI in Transfer Pricing?
AI in transfer pricing refers to the use of artificial intelligence and automation to support tasks such as transaction-data analysis, functional analysis, comparable-company research, benchmarking and documentation. It can help organise information and reduce repetitive work, but the final economic analysis must be reviewed by a qualified professional.
2. How Can AI Help with Transfer Pricing Benchmarking?
AI can assist with organising company information, applying screening criteria, comparing available financial indicators and preparing supporting analysis. The analyst must still determine whether selected companies are economically comparable and whether the method and results are appropriate.
3. What Is TP DOC GEN AI?
TP DOC GEN AI is SBC's AI-powered transfer pricing technology platform. Its public product information describes workflows for entity onboarding, benchmarking, economic analysis and transfer pricing documentation. Visit the TP DOC GEN AI website for product information.
4. Can AI Prepare Transfer Pricing Documentation?
AI-assisted tools can help organise source information, draft narratives, structure calculations and assemble documentation. The resulting documents must be checked for accuracy, completeness, appropriate methodology and consistency with applicable rules. Automated generation alone does not establish compliance.
5. Does AI Change the Arm's-Length Principle?
No. AI does not replace the arm's-length principle or applicable transfer pricing legislation. Technology may support the analysis, but the conclusion must be based on transaction facts, reliable evidence and an appropriate application of relevant rules.
6. Do UAE Businesses Need to Consider Transfer Pricing for Domestic Transactions?
UAE transfer pricing rules can apply to transactions between related parties and connected persons even when both parties are in the UAE. Requirements depend on applicable legislation and the facts of the business. Consult the Federal Tax Authority's Corporate Tax FAQs and a qualified adviser.
7. Can AI Replace a Transfer Pricing Adviser?
AI can assist with information processing, research and documentation, but it should not replace professional judgement. Advisers must assess commercial facts, evaluate comparability, apply appropriate methods, verify evidence and review final conclusions.
8. What Should a Business Check Before Adopting Transfer Pricing AI?
Evaluate analytical capabilities, source traceability, confidentiality, access controls, review and approval processes, compatibility with existing systems and the ability to produce required documentation. A controlled pilot with measurable outcomes is a practical way to assess suitability.
9. How Does Transfer Pricing Connect with Corporate Tax and Pillar Two?
Transfer pricing affects how profit is allocated between related entities. Those accounting results may feed into corporate tax calculations and, for multinational groups within scope, Pillar Two calculations. The rules differ by regime, so businesses should reconcile the underlying data while applying the correct requirements separately.
10. Where Can Businesses Learn More About AI-Powered Transfer Pricing Analysis?
Businesses can visit TP DOC GEN AI for product information, the UAE Federal Tax Authority's Transfer Pricing Guide for local context, and SBC's transfer pricing services and insights for practical guidance.
Disclaimer
This article is provided for general informational and educational purposes only. It does not constitute legal, tax, financial or other professional advice and should not be relied upon as a substitute for advice tailored to specific circumstances. Tax laws, regulations, administrative guidance and technology capabilities may change. Readers should verify the latest requirements through relevant official government and regulatory sources, including the UAE Ministry of Finance and Federal Tax Authority, and consult a qualified professional before making decisions or taking action.